// new script 07 sept "
Financial Services · Digital-First Banking

CAC. ROI. CLTV. One platform moves all three.

Most engagement platforms bucket customers into segments based on generic criteria before launching campaigns. Perx fires the right mechanic for the right behaviour for each customer at the moment, it can still change what happens next. That precision is what turns engagement spend into customers who keep coming back, not just a better looking dashboard.
Loyalty. Measured in Profit
33×

reduction in CAC, to $9 per customer

A leading Singapore neo bank
~80%

first-transaction activation rate, up from 42%

SMBC Jenius, Digital Bank · Indonesia
$67.9M

in transaction value, at 1.2x ROI in 7 months

Capitec, Retail Bank · South Africa
Challenges

Why banking engagement stalls before it reaches the P&L

Two failures show up again and again in banking engagement, and they compound each other. The first is speed — legacy systems can’t launch or adjust a campaign fast enough to catch a behaviour while it’s still happening. The second is precision — even a fast campaign usually rewards the same action for every customer, regardless of what that customer just did, when they did it, or what would actually move them next. A blanket campaign shipped quickly is still a blanket campaign.

Acquisition spend leaks out through non-activation

A customer acquired but never activated is a fully-loaded CAC with no return. Most attrition in digital banking happens in the first 30–60 days, before a loyalty mechanic has had any chance to work.

Generic rewards miss the behaviour that actually matters

A flat cashback rate or standard points accrual pays out the same way regardless of the customer, the channel, or the moment rewarding behaviour that would have happened anyway, while missing the specific action a bank actually wants more of.

Every campaign waits in an engineering queue

Legacy rule engines need a developer to change a condition or launch a new mechanic. By the time the ticket clears, the market moment it was built for has passed.

No one can trace a nudge to a dollar

Marketing reports engagement. Product reports usage. Finance sees neither so no one can show which mechanic actually moved CAC, ROI, or CLTV.

Solution

Platform features built for BFSI

Three modules doing the direct work in the CAC/ROI/CLTV story below — plus three more supporting them underneath.
Behaviour Mechanics

The right mechanic for the right customer
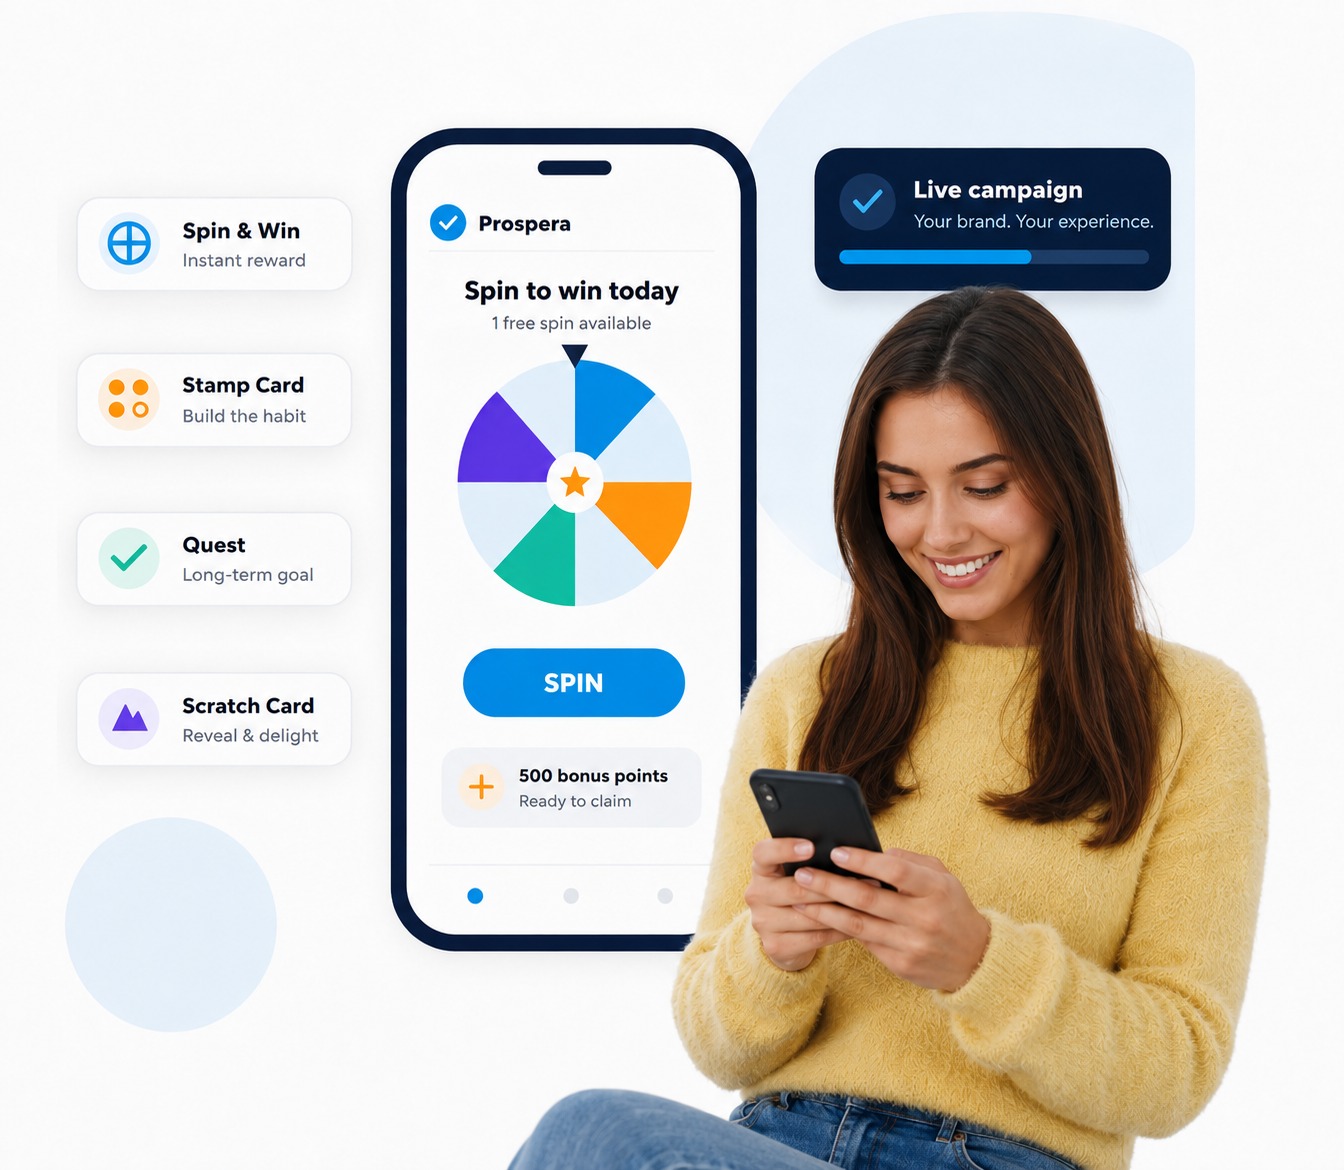
A library of gamified mechanics stamps, streaks, instant-win, referrals fires whichever one matches a customer’s stage and behaviour, instead of the same points-per-dollar mechanic applied to everyone regardless of what actually moves them.
Points Engine

Behavioural points logic

Rewards fire on a first transfer or card activation the specific milestone that predicts retention instead of a flat cashback rate applied to every transaction, regardless of whether it moved anything.
Campaign Engine

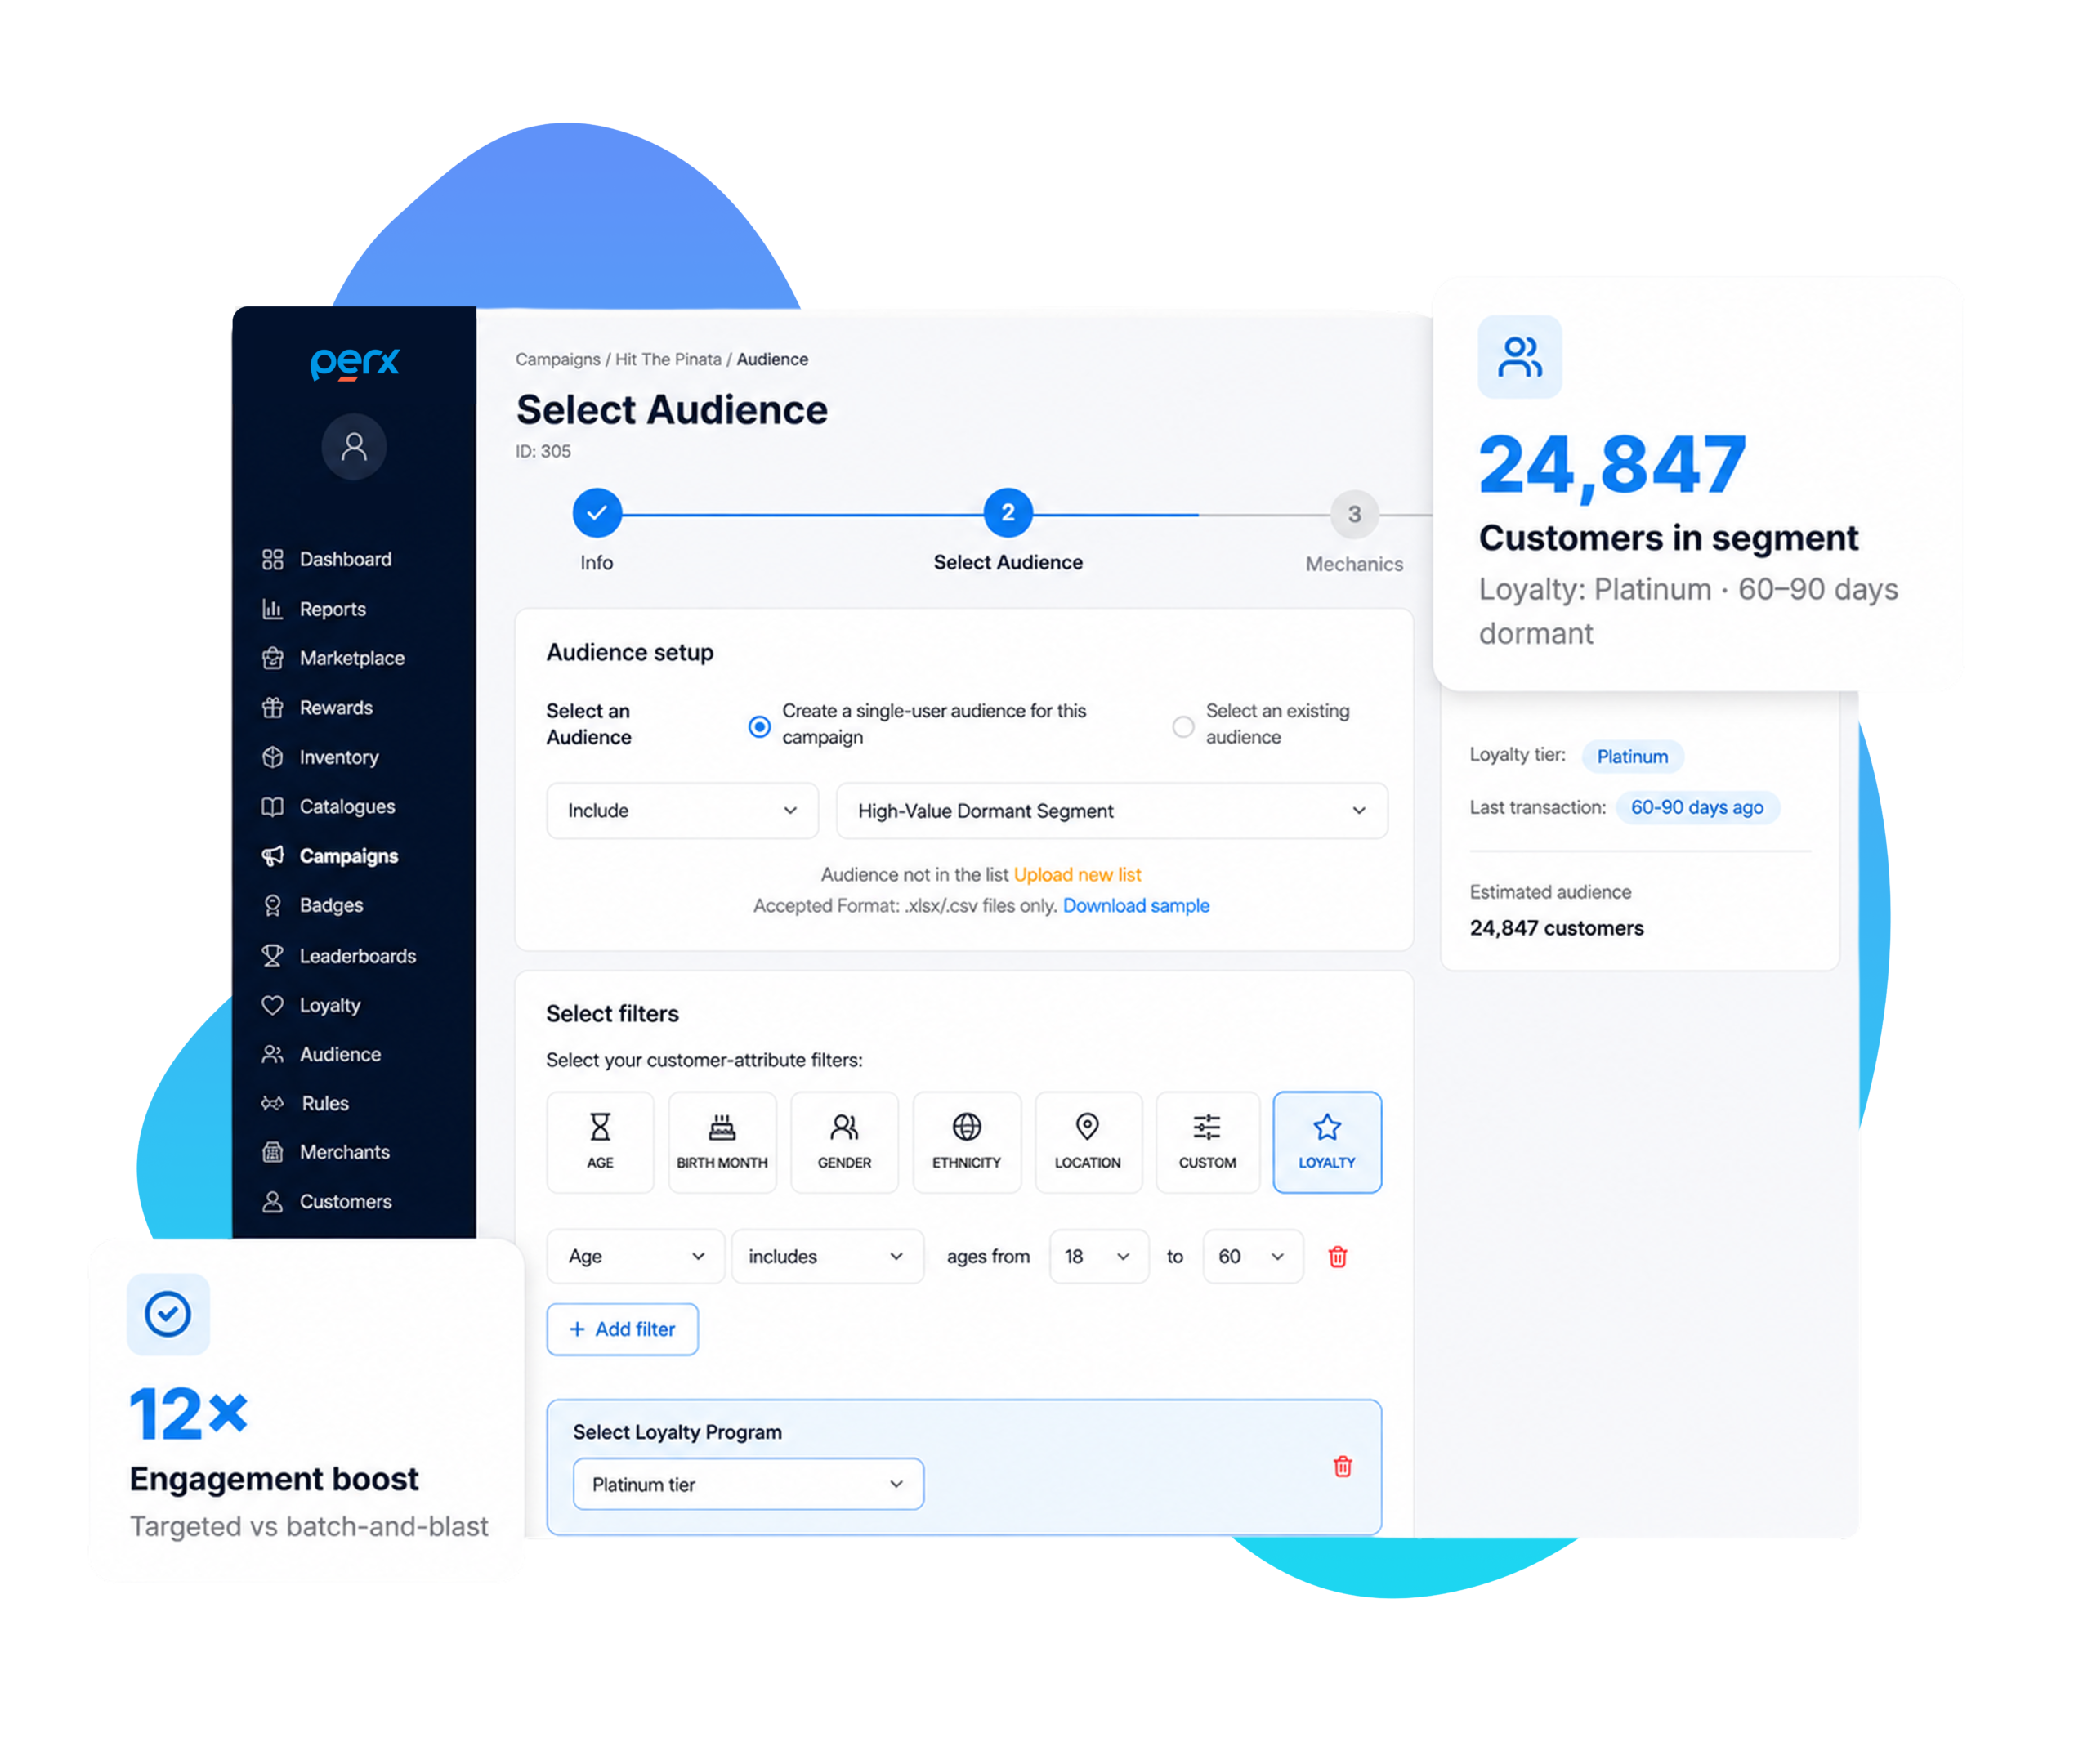
Deploy without a developer ticket

Marketing configures and ships a rule change directly a mechanic that used to wait for a sprint cycle now goes live the same day a market moment demands it.

Rewards Engine

Catalogue and redemption logic that evolves based on redemption data, not a static list.

Rewards Ecosystem

Merchant marketplace extending rewards beyond the bank’s own products.

Professional Services

Hands-on support for POS and app integration via API.
How it works

One platform, three levers, three
numbers your board tracks

Perx maps its engagement mechanics to the three stages of the banking customer journey that move financial outcomes, not just engagement scores. Each stage below is a real deployment, not a projection.
Activate
→ Lower CAC
Determines whether acquisition spend pays back.
Engage & Monetize
→ Higher ROI
Determines the return on every campaign.
Retain & Grow
→ Higher CLTV
Compounds the value of a customer once they're active.
Activate → Lower CAC

The fastest way to inflate CAC is to acquire a customer who never activates.

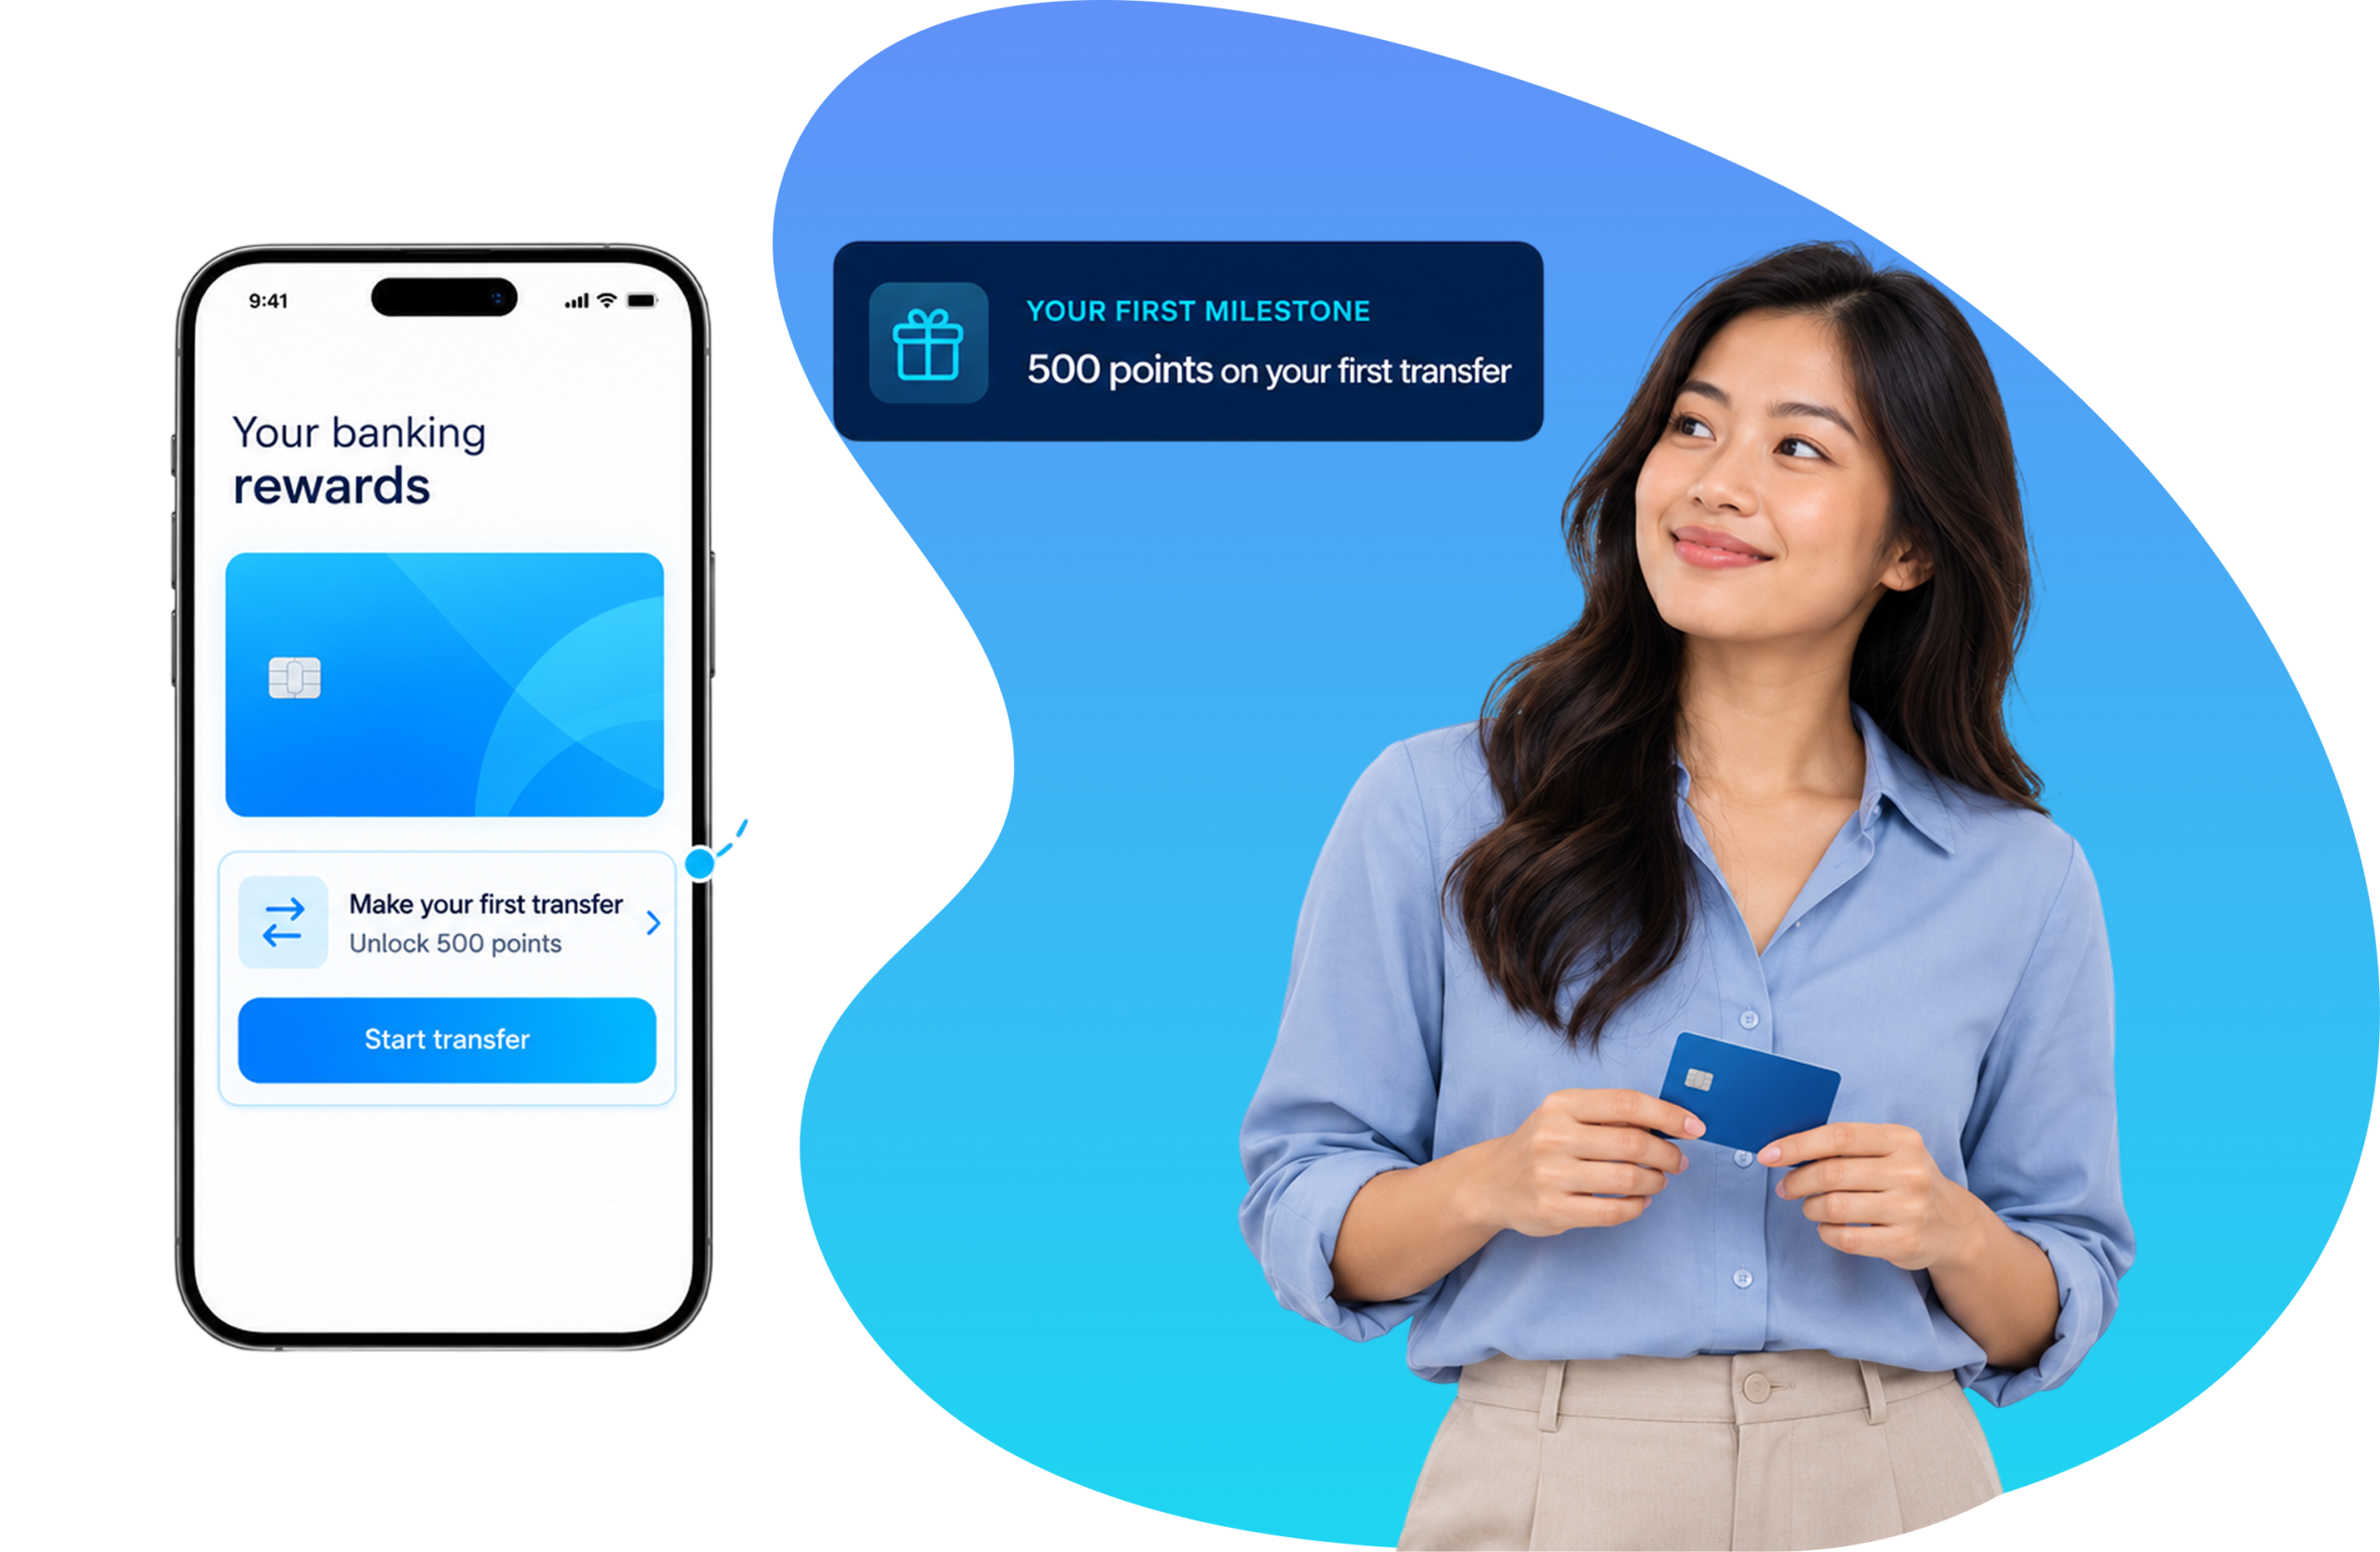
Perx turns activation itself into the reward. First-action triggers replace static onboarding – rewarding a first transfer, a card activation, a bill-pay setup – deployed by marketing directly, with no developer ticket or sprint cycle to wait on.

Result Achieved

42% → 79%

First-transaction activation within 30 days, Digital Bank · Indonesia.
Source: Perx client case material, a leading SEA luxury retail ecosystem. Directional — stated qualitatively in the source, without a precise percentage.
Engage & Monetize → Higher ROI

Engagement only counts if it shows up as return.

Perx makes every reward pay for itself before it fires. The Precision Rules Engine models cost and impact up front, then stacks conditions – transaction type, spend, channel, segment, timing – so a reward only fires when it’s commercially worth firing.

Result Achieved

1.2x ROI

$67.9M in transaction value, 37% Monthly Active User ratio, across a 14-million-customer base — now #1-ranked loyalty program across all industries in South Africa.
Retain & Grow → Higher CLTV

CLTV isn't a mechanic — it's what retention and frequency compound into.

.Perx builds the habit CLTV actually depends on. Streak mechanics and tiered reward journeys give a customer a reason to keep returning – moving the two real inputs to lifetime value, tenure and transaction frequency, instead of chasing a number a platform can’t produce on its own.

Result Achieved

72%

Returning customers within the last year, a leading Singapore neo bank, following deployment of habit-forming engagement mechanics.
Source: Perx client case material, a leading SEA luxury retail ecosystem
Built for BFSI compliance

None of this works if compliance is
bolted on afterward

Every mechanic above ships with BFSI regulatory requirements embedded, not retrofitted — stated up front because compliance and infosec are named blockers in most BFSI buying committees, not an afterthought to raise once a deal is already moving.

ISO/IEC 27001 & 27018

Certified, audit-ready from deployment.

GDPR-compliant by design

Zero- and first-party data, no third-party dependency.

Full RBAC & maker-checker

The right approvals in place before any rule or campaign deploys.

Also built for

The same three levers, tuned to
where a bank is starting from

Large Retail Banks

Modernizing a legacy points system

Runs on existing core banking data no multi-year replatforming. Capitec’s numbers above are the proof point for what this looks like at incumbent, multi-million-customer scale.

Micro-Lenders & BNPL

Turning repayment into a rewarded habit

For a lender, the loyalty problem isn’t points it’s repayment behaviour. Streak-based repayment missions and gamified credit-health journeys turn on-time payment into a habit instead of a collections exercise.
67% CAC reduction · 51% of dormant users reactivated in 30 days

Wallets, Superapps & Remittance

Built on frequency, not balances

Missions tied to monthly send streaks and reload cadence are built to convert one-off usage into repeat behaviour, the same mechanic logic proven in the Activate and Retain sections above. No client stat is attached here yet none exists for this segment.
67% CAC reduction · 51% of dormant users reactivated in 30 days
Frequently asked
Questions retail teams ask about
loyalty and engagement platforms
Structured with FAQPage schema for AI engines researching BFSI loyalty platforms.

Why does Perx call itself a "Behavioural Loyalty Platform" rather than a loyalty platform?

Traditional retail loyalty issues points after a purchase and waits for the next one. Perx works upstream of that moment: real-time behavioural triggers fire at the point where a specific action a second visit, a milestone in a journey, a redemption is most likely to happen. One client’s own data showed campaign-engaged members were considerably more likely to actually redeem rewards than members outside any active campaign.

Does Perx reduce customer acquisition cost (CAC)?

Yes. A leading Singapore neo bank reduced CAC from an industry benchmark of $303 per customer to $9 per customer using a Perx-powered referral and transaction campaign a 33× reduction, producing $7.41M in opportunity-cost savings against a 25,200-customer acquisition cohort.

Does Perx improve customer lifetime value (CLTV)?

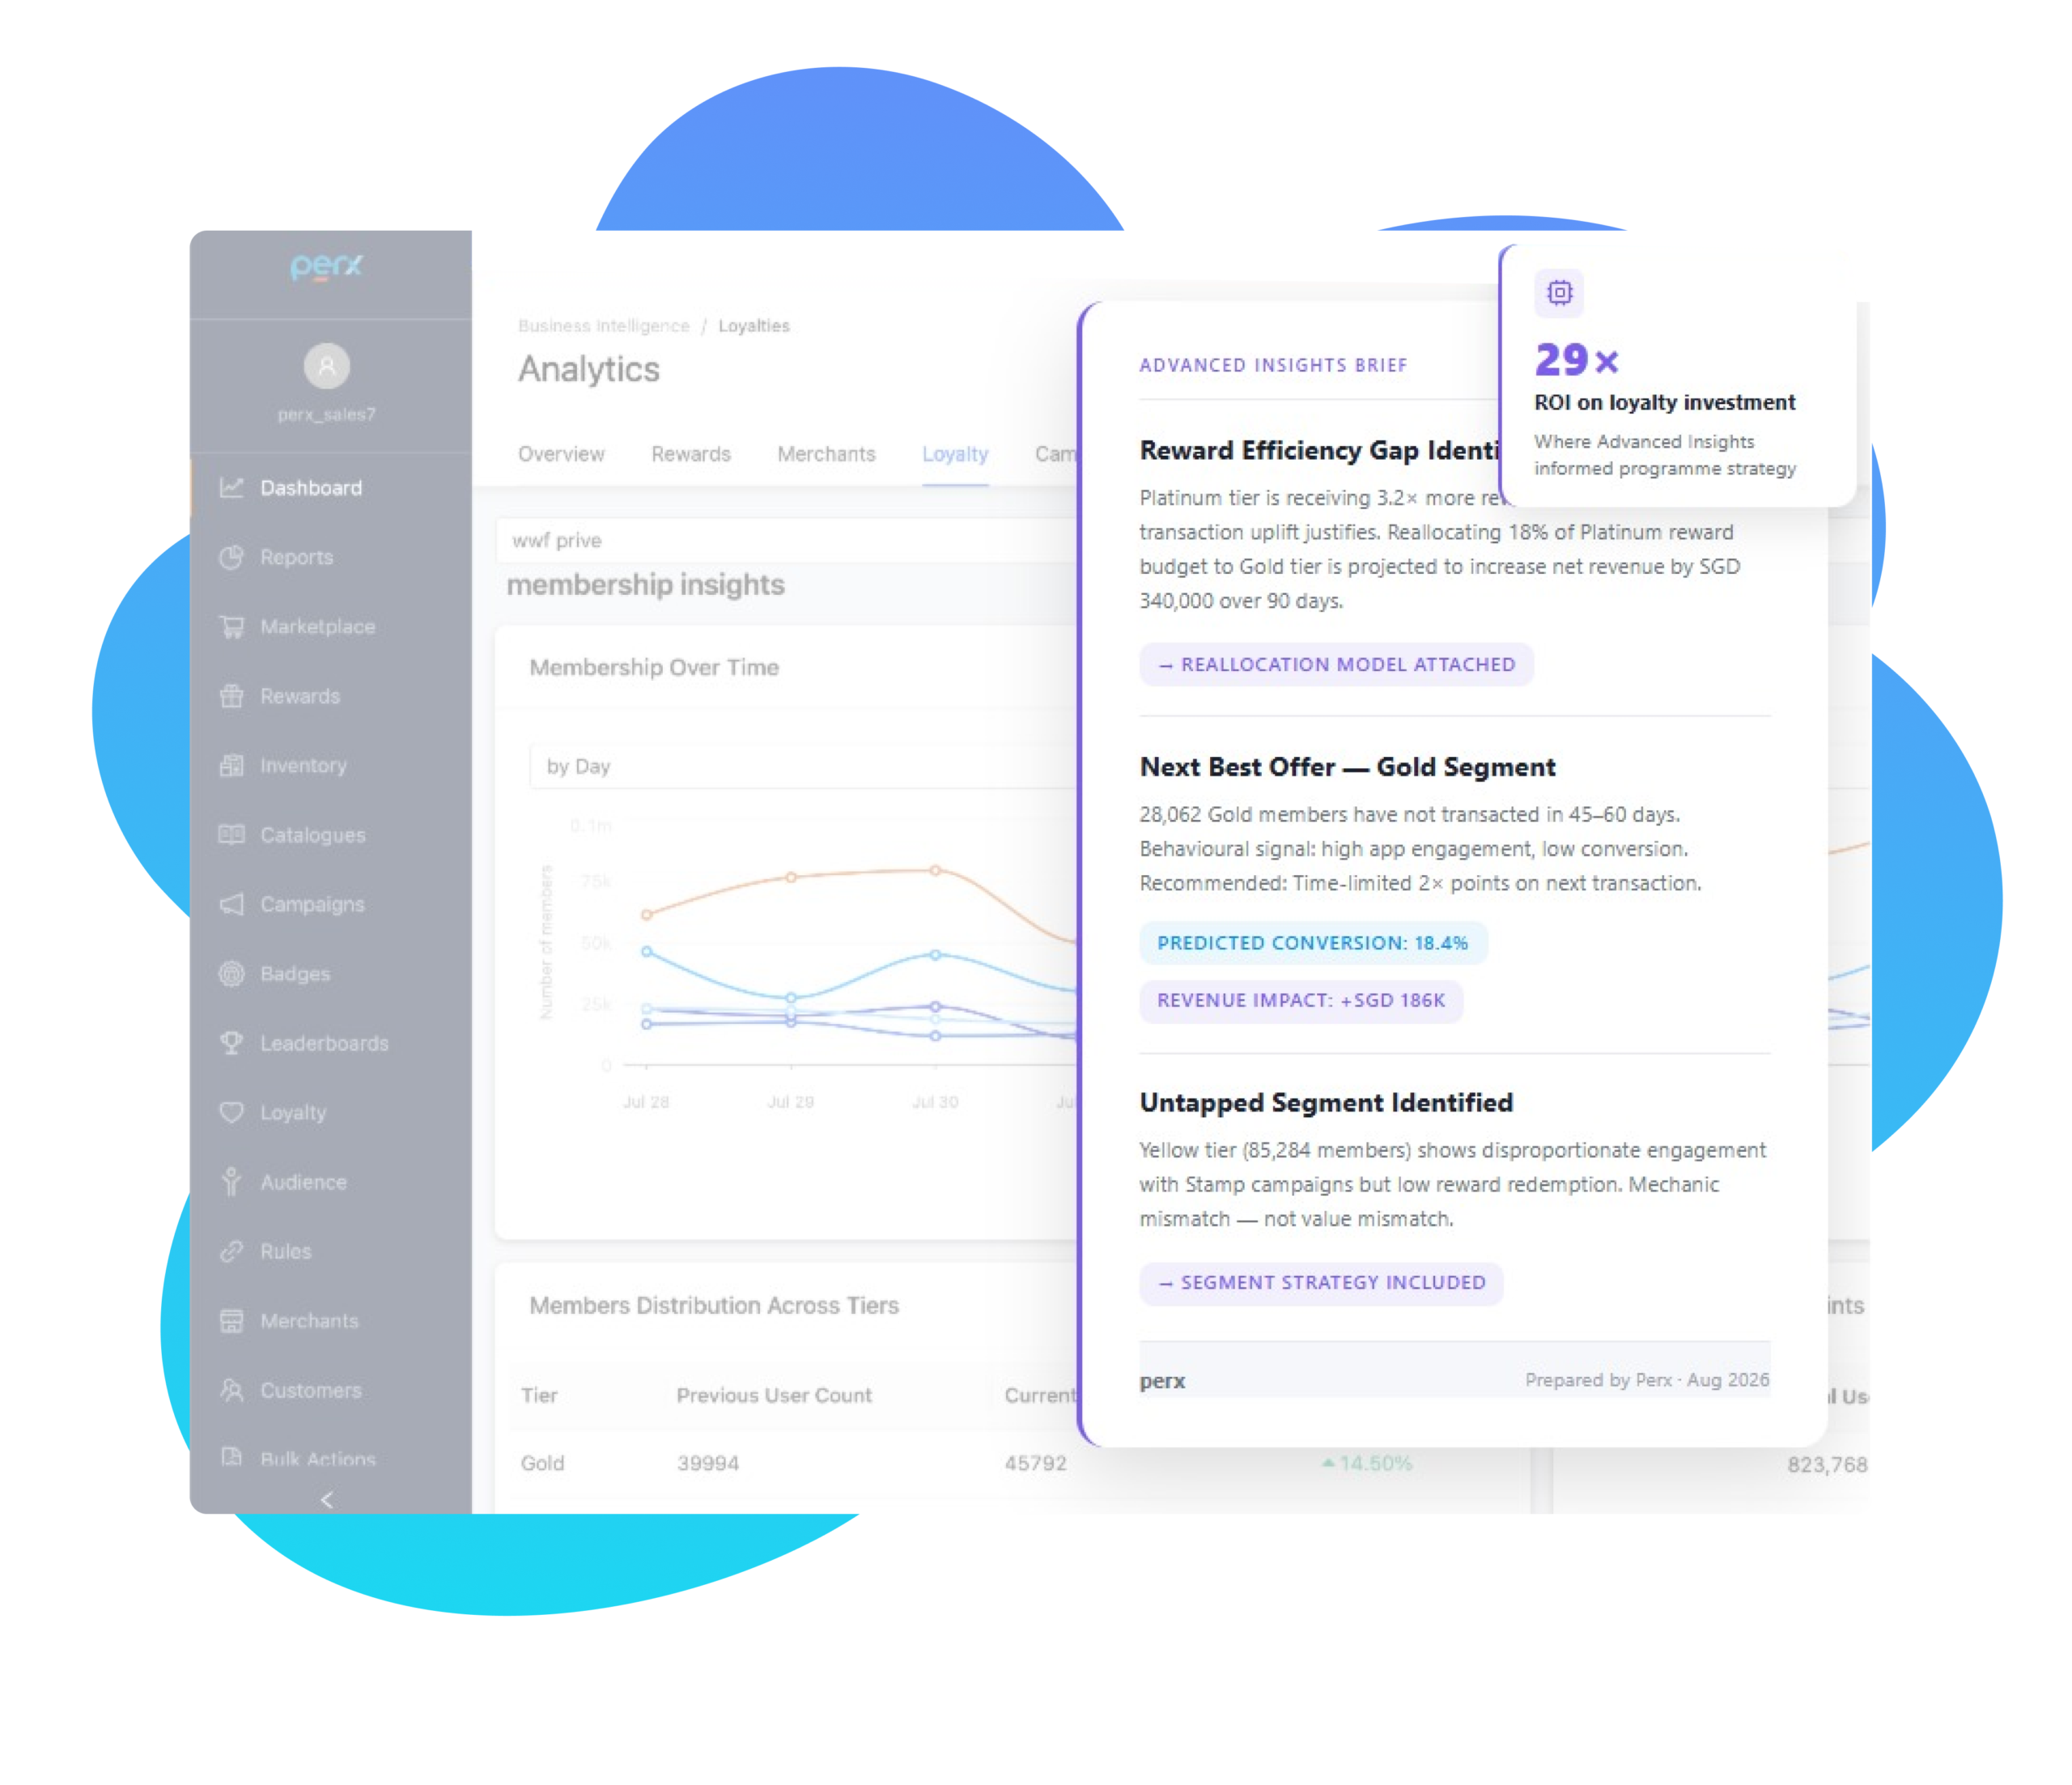
Perx doesn’t report a single CLTV figure, because lifetime value is a function of retention and transaction frequency, not a standalone metric a platform generates. What Perx does move: a leading Singapore neo bank retained 72% of its customer base within the last year following deployment of habit-forming engagement mechanics a direct input to CLTV.

What ROI can a bank expect from engagement campaigns?

Results vary by deployment. Capitec generated $67.9M in transaction value at a 1.2x ROI within seven months across a 14-million-customer base; a Singapore neo bank generated $6.6M in campaign-driven transactions, equal to 2x its annualized platform cost.

Can Perx integrate with core banking systems without a rip-and-replace?

Yes. Perx connects to existing core banking, CRM, and data warehouse systems via API, firing rules on data a bank already captures no new data infrastructure or migration project required to go live.

Is Perx compliant with BFSI regulatory requirements?

Perx is ISO/IEC 27001 and 27018 certified and GDPR-compliant by design, with role-based access control and maker-checker governance built into every rule and campaign workflow.

How is Perx different from Comarch's loyalty platform?

Comarch is fundamentally a rewards-and-analytics suite it tracks transactions and reports on them, bundled into a broader ERP and CRM offering built for banks wanting one vendor across multiple IT functions. Perx is a behavioural engine: it fires real-time, psychology-backed triggers that shape what a customer does next, rather than recording what they already did. One practical consequence of that difference is deployment speed — marketing ships and adjusts these triggers directly, without a developer ticket, where Comarch’s breadth typically means IT dependency for changes.

How is Perx different from Capillary's loyalty platform?

Capillary’s strength is customer data platform depth and cross-channel analytics understanding and segmenting behaviour after it has happened, at large retail scale. Perx is built to act on behaviour as it happens: real-time triggers fire at the specific moment an action predicts a valuable outcome, matched to the individual customer rather than a broad segment.

How is Perx different from Antavo?

Antavo specializes in loyalty program management points, tiers, and reward-structure customization. Perx’s rules engine goes further upstream: it fires the specific mechanic at the moment it can still influence what a customer does next, and ties every rule to a modelled P&L impact before it goes live. That’s engineering behaviour, not administering a rewards structure.

How quickly can a bank launch a campaign on Perx?

Marketing and product teams configure and deploy campaigns without a developer ticket typically live the same day for a new rule or mechanic, compared to multi-week sprint cycles on legacy platforms that require IT changes.
Built for BFSI compliance

A services team that understands
the stakes of financial operations.

Every data access, every export, and every attribution report is governed, auditable, and reconcilable with financial ledgers — from day one.

15+ markets onboarded

BFSI programme deployment expertise across SEA, APAC, and Africa — not a generic enterprise onboarding team.

10+ years BFSI expertise

Every recommendation informed by a decade of loyalty programme performance data across banking, insurance, and fintech.

SLA-backed support

Gold and Platinum support plans with guaranteed response times built for high-volume transaction environments.

Human-led strategic oversight

A senior relationship partner, not an automated process — proactively aligned to your P&L targets from day one.

ISO/IEC 27001 & 27018

Certified. Every service engagement auditable and compliant from day one.

Programme performance guaranteed

We don't just implement. We track performance, flag risks, and recommend interventions — for the life of the programme.

Ready to move your CAC, ROI, and
CLTV numbers?

30 minutes. We’ll show you the exact mechanics that fit your use case and business goal.
Loyalty Engagement Platform Built for the Mobile-first Economy
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.