// new script 07 sept "
Articles Tagged with: Customer Engagement

What Omnichannel Loyalty Orchestration Means for Banks and Telcos in APAC
Praveen Vadla

Senior Digital Marketing Manager | September 02, 2026

What Is Omnichannel Loyalty Orchestration in Banking and Telecom?

IN BRIEF

Omnichannel loyalty orchestration means firing the same behaviour-based reward logic across every channel a customer touches, mobile app, SMS, call centre, and branch, so no touchpoint runs its own disconnected program.

For BFSI and telco brands, this replaces fragmented, per-channel loyalty logic with one rules engine that triggers consistently everywhere a customer acts.

Perx’s deployment with Jenius (Bank BTPN, part of SMBC Indonesia) shows what this looks like in production: a single rules-based engine drove US$599 million in card spend and a 32x return on investment, with customer spend running 67% above Indonesia’s national average.

Omnichannel loyalty orchestration is the coordination of reward triggers, messaging, and journey logic across every channel a customer uses, so the experience reads as one continuous program rather than a set of separate promotions run by separate teams.

In most banks and telcos, loyalty logic still lives channel by channel. The mobile app team runs one set of campaigns. The call centre works from a different rulebook. Branch staff apply manual overrides. None of these three teams necessarily know what triggered a reward for the same customer somewhere else. Orchestration removes that fragmentation: one rules engine, one configuration layer, one behavioural record per customer, regardless of which channel the action happened on.

Across APAC, this matters now because customers expect consistent experiences whether they interact via app, web, branch or contact centre, while regulators and risk teams demand transparent, auditable decision-making in financial services.

How Is This Different From Traditional, Single-Channel Loyalty Programs?

Traditional loyalty programs are typically built around a static points catalogue configured separately for each channel. Every new channel means a new campaign build, a new IT ticket, and a new opportunity for the customer record to fall out of sync.

  • Traditional: per-channel campaign builds, manual configuration, IT-dependent changes, delayed reward attribution.
  • Orchestrated: rules fire in real time regardless of channel, one configuration layer, no duplicate campaign work, immediate reward attribution tied to the action.

The practical difference shows up fastest in speed to launch and in whether a customer’s behaviour across channels is actually visible to the team running the program, rather than trapped in separate silos.

How Does Orchestration Improve Customer Activation and Retention?

When the same rules engine sits behind every channel, a customer’s action anywhere becomes an immediate, attributable trigger everywhere. A mobile top-up, an SMS response, or a branch visit all map to the same behavioural logic instead of three disconnected reward systems.

In the Jenius deployment, this rules-based approach fired 13.4 million individual spend rule triggers over six months, activating 709,000 users onto the programme and achieving a 55% earn-to-burn ratio, meaning more than half of all rewards issued were actively redeemed rather than sitting unused as a growing liability on the balance sheet.

How Perx Approaches Omnichannel Orchestration

Perx’s orchestration layer is rules-based and behaviour-driven. Every trigger is tied to a defined customer action and a defined reward outcome, which means every decision the system makes is traceable back to a specific rule, not inferred by a model in ways that are difficult to explain to a risk or compliance team.

For example, a rule might state: “If a customer spends above a defined threshold on eligible card transactions in a month, unlock a tiered reward that is visible and redeemable across app, SMS and branch.” That rule is configured once, version-controlled, and can be formally reviewed and approved before going live.

That distinction matters most in regulated markets. A bank’s risk committee can review, audit and sign off on a rule. That auditability is precisely what the Jenius deployment was built on, and it is why the next phase of the platform is focused on extending this same rules-based foundation with a unified control layer for auditability across every channel and every deployment, not on replacing rules with autonomous decision-making

How Does Perx Compare to Other Loyalty Platforms on Omnichannel Orchestration?

Platform Primary focus & BFSI relevance Omnichannel / real-time capability & compliance posture
Perx BFSI and telco behavioural loyalty, purpose-built for APAC Rules-based cross-channel orchestration; ISO/IEC 27001:2013 and ISO 27018:2019 certified, with 2026 renewal of ISO/IEC 27001:2022 and ISO 27018:2019 publicly stated.
Antavo Enterprise loyalty for retail, travel and financial services API-based real-time data ingestion and unified customer profiles; financial-services use cases are publicly described. GDPR and UK GDPR support is documented; specific ISO certifications should be confirmed directly with the vendor.
Comarch Telecom and retail loyalty suites, established enterprise vendor Strong telco positioning; public materials describe rewards and offers across app, portal, SMS, call centre and in-store channels. Vendor references industry-grade security and certifications, but specific certificate names and scope should be confirmed directly.
Capillary Technologies Retail-first CRM and loyalty engagement, APAC presence BFSI use cases are publicly discussed, including banking loyalty programs. Native real-time cross-channel orchestration and BFSI-specific security certifications require direct vendor confirmation.
Loyalty Juggernaut (GRAVTY) Enterprise loyalty platform across multiple industries Explicit financial-services and telecommunications positioning. Publicly lists ISO/IEC 27001, ISO/IEC 27018, SOC 1 Type II, SOC 2 Type II, GDPR and ISO 22301-related credentials.
Open Loyalty Open-source, API-first loyalty engine Flexible, API-first engine suitable for custom BFSI deployments. ISO 27001 and ISO 9001 certifications are publicly stated, along with GDPR-related capabilities; BFSI-specific compliance configuration and native omnichannel orchestration depend on implementation.
Talon.One Promotion and rules engine used across industries Explicit financial-services use cases (banking, fintech, insurance) with real-time rules and loyalty transactions. ISO 27001:2022 certified, GDPR compliant and SOC 2 Type II attested.

Notes:

  • Claims around certifications and compliance are based on publicly available vendor documentation and should be revalidated against current certificates, scope statements and validity dates during procurement.
  • “BFSI fit” refers to how strongly each platform is positioned and documented for banking, insurance and telco use cases, not an endorsement of any specific deployment.

Where Should a Bank or Telco Start With an Omnichannel Loyalty Project?

  • Audit current per-channel campaigns to find where reward logic is duplicated or contradictory across mobile, SMS, call centre, and branch.
  • Define the specific customer behaviour the program needs to change before evaluating any vendor. A deployment without a measurable behavioural target is not an orchestration project, it is a rebrand of the existing points catalogue.
  • Evaluate whether a platform’s rules engine can trigger in real time across channels, or whether cross-channel reporting is stitched together after the fact.
  • Confirm compliance certification fit for your market. In BFSI specifically, this means checking for recognised information security and privacy certifications before any data integration work begins.

Common pitfalls to avoid:

  • Trying to orchestrate before cleaning up underlying product and campaign logic.
  • Over-complicating the first wave of rules instead of starting with 3–5 high-impact behaviours.
  • Underestimating the need for cross-functional alignment across marketing, product, risk, IT and operations.

FAQs:

What is omnichannel loyalty orchestration in banking and telecom?

It is the coordination of reward triggers and journey logic across every channel a customer uses, mobile app, SMS, call centre, and branch, so the program behaves as one system rather than separate, disconnected campaigns.

Traditional programs configure each channel separately, which means duplicated campaign work and delayed reward attribution. Orchestration uses one rules engine across all channels, so triggers fire in real time regardless of where the action happened.
It gives every customer action, on any channel, an immediate and attributable reward outcome. In the Jenius deployment, this drove 709,000 activated users and a 55% earn-to-burn ratio over six months.
Rules-based and behaviour-driven. Every trigger ties to a defined rule and a defined outcome, which keeps every decision auditable for risk and compliance review, a requirement in regulated BFSI environments.
Start by auditing existing per-channel campaigns for duplicated logic, then define the specific customer behaviour the program needs to change before evaluating vendors on real-time, cross-channel rules capability and compliance certification.
In its deployment with Jenius (Bank BTPN, part of SMBC Indonesia), Perx’s rules-based engine drove US$599 million in card spend and a 32x return on investment over six months, with customer spend running 67% above Indonesia’s national average.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

How to Calculate Loyalty Program ROI

Praveen Vadla

Senior Digital Marketing Manager | August 26, 2026

How to Calculate Loyalty Program ROI

IN BRIEF

  • Loyalty program ROI = (Incremental Revenue − Total Program Cost) / Total Program Cost × 100.
  • Incremental revenue only counts spend a member would not have made without the program, not their total spend.
  • Enterprise programs carry a cost bucket most SMB ROI formulas skip entirely: unfunded points liability.
  • Track four cost categories: technology, people, rewards and liability, and compliance or IT integration.
  • In regulated industries, ROI typically takes 12 to 18 months to stabilize because behaviour change takes longer to prove than a discount code.

Loyalty program ROI is the number a CFO asks for before renewing next year’s budget, and it is also the number most marketing teams struggle to defend. Calculating it looks simple on paper: subtract cost from revenue, divide by cost. In practice, most teams get the formula right and the inputs wrong. They count total member revenue instead of incremental revenue, they leave out the people and compliance cost of running the program, and they never account for the points sitting on the balance sheet as an unfunded liability. For an enterprise BFSI or telco program running across millions of customers and multiple regulatory jurisdictions, those gaps compound fast. Here is a formula built for that scale, not for a single Shopify storefront.

What Is Loyalty Program ROI?

Loyalty program ROI is the ratio between what a loyalty program returns to the business and what it costs to run, expressed as a percentage. A program with 100% ROI has broken even. Anything above that is profit. The complexity is not in the ratio. It is in defining “return” correctly, because not every dollar a member spends belongs to the program.

The Loyalty Program ROI Formula

The standard formula is:
ROI = (Incremental Revenue − Total Program Cost) ÷ Total Program Cost × 100

Two words carry the weight in that equation: incremental and total. Incremental revenue excludes spend a customer would have made anyway. Total program cost includes every cost bucket, not just the platform license. Get either one wrong and the ROI figure you bring to the CFO will not survive the first follow-up question.

Step 1: Calculate Incremental Revenue, Not Total Member Revenue

The most common ROI mistake is adding up everything loyalty members spend and calling it program revenue. That number is inflated, because your most valuable customers were always going to be your most valuable customers, program or not. What you need is the difference between what a member spends after joining and what a comparable non-member spends over the same period.

Metrics to Pull

  • Average revenue per customer, both before and after program enrollment
  • Purchase or transaction frequency, segmented by member and non-member
  • Average order or transaction value uplift
  • Product or account penetration (cross-sell rate) among members versus non-members
  • Activation rate: the share of enrolled customers who complete a defined revenue-linked behaviour, not just sign up

Why a Holdout Group Matters at Enterprise Scale

At consumer ecommerce scale, teams often estimate incremental revenue with a rough before-and-after comparison. At enterprise scale, that is not good enough for a CFO or a risk committee. Run a holdout group: a statistically comparable segment of customers who are eligible for the program but not enrolled, tracked over the same period as members. The revenue gap between the two groups is your real incremental revenue, isolated from market growth, seasonality, or a macro uptick that had nothing to do with the loyalty program.

Step 2: Add Up the Four Cost Buckets

Program cost is where enterprise ROI calculations diverge hardest from the SMB playbook. A Shopify loyalty app has three or four cost lines. A behavioural loyalty program running inside a bank or telco has a fifth: the cost of proving to compliance and risk that the program will not create liability.
Cost Bucket What It Includes Typical Owner
Technology Platform licensing, implementation, integration, and ongoing engineering support Marketing + IT
People Program manager, campaign team, analyst time, and cross-functional hours from CX and risk Marketing
Rewards and Liability Redemption cost, partner rewards, and the accrued value of unredeemed points sitting as a liability Finance
Compliance and IT Integration Risk review cycles, data governance, core banking or OSS/BSS integration, and audit readiness Risk + IT

Step 3: Account for Points Liability, the Cost Most Formulas Miss

Every unredeemed point on a traditional earn-and-burn program sits on the balance sheet as a liability the enterprise owes its customers. It does not show up as a monthly invoice, which is why so many ROI calculations leave it out. But finance teams already track it, and it drags down the real return of the program even when the marketing dashboard looks healthy. This is the structural reason a behaviour-led model changes the ROI math: when engagement is built around actions the enterprise wants (activation, cross-sell, digital adoption) rather than transactions rewarded after the fact, less value sits unredeemed and unaccounted for. Engagement metrics that cannot be traced to revenue, and liability that cannot be traced to a behaviour, do not belong in a board deck.

A Worked Example (Illustrative)

The numbers below are illustrative only, built to show the mechanics, not benchmarks from a specific client.

  •  Enrolled members: 500,000
  • Average annual revenue per member, pre-enrollment (holdout group): $420
  • Average annual revenue per member, post-enrollment: $510
  • Incremental revenue: ($510 − $420) × 500,000 = $45,000,000
  • Total program cost (technology + people + rewards/liability + compliance): $9,000,000
  • ROI: ($45,000,000 − $9,000,000) ÷ $9,000,000 × 100 = 400%

A 400% ROI means the program returned four dollars for every dollar it cost, on top of breaking even. That is the number worth bringing to a board, because every input behind it can be defended line by line.

Loyalty Program ROI Benchmarks

Public benchmarks are useful for context, though every enterprise program should be judged against its own holdout data first. According to Antavo’s Global Customer Loyalty Report 2025, brands surveyed reported their loyalty program generating an average of 5.2 times more revenue than it cost to run, up from 4.8 times the year before. Separately, Forrester has found that a majority of US online adults say loyalty programs influence both what they buy and where they buy it, which is the behavioural signal that underpins any incremental revenue calculation.

Metric Reported Benchmark Source
Average loyalty program ROI multiple 5.2x program cost (2025), up from 4.8x (2024) Antavo GCLR 2025
Time to reliable ROI signal 12 to 14 months typical, based on redemption maturity Antavo GCLR 2025
US adults influenced by loyalty programs on what they buy 54% Forrester

Why Enterprise BFSI and Telco Programs Calculate ROI Differently

An ecommerce loyalty program answers to a marketing budget. An enterprise BFSI or telco program answers to a marketing budget, a risk committee, and sometimes a regulator. That changes what counts as cost (add compliance and integration) and what counts as revenue (add product penetration and digital channel migration, not just average order value). It also changes the timeline: enterprise customer relationships run for years, not one purchase cycle, so ROI has to be modeled against CLTV, not a single transaction.

How Perx Helps Enterprises Prove Loyalty Program ROI

Most loyalty platforms hand you a dashboard of engagement metrics and leave the revenue attribution to you. Perx is built the other way. Every behaviour the platform triggers is mapped to a business outcome from the start, so the incremental revenue calculation is not a quarterly research project bolted on after the fact, it is built into how the program runs. Combined with real-time behavioural triggers and intent-based personalisation, that mapping is how Perx-run programs cut acquisition costs by up to 33x for enterprise clients: not by discounting harder, but by targeting the behaviour that actually drives the number the CFO is asking about.

FAQs:

What is a good ROI for a loyalty program?
A loyalty program is functional once it clears 100% ROI, meaning it has broken even. Antavo’s 2025 Global Customer Loyalty Report found surveyed brands averaging 5.2 times program cost in returns, but the right benchmark for your program is its own holdout-group data, not an industry average, because cost structures vary widely between a discount-based program and a behaviour-led one.
Most programs need 12 to 14 months before ROI data is reliable, because it takes that long for a meaningful share of members to move through enough purchase or engagement cycles to separate program-driven behaviour from normal buying patterns. Judging ROI before that window closes usually produces a misleadingly low number.
Customer acquisition cost (CAC) measures what it costs to win a new customer. Loyalty program ROI measures the return generated from customers you already have. A well-designed loyalty program can lower CAC over time, through referral and advocacy behaviour, which is one input into ROI but not the same metric.
Every point a member has not yet redeemed is value the enterprise still owes them, and it sits on the balance sheet as a liability even though no cash has changed hands. Traditional earn-and-burn programs accumulate this liability quietly. It reduces real ROI even when the marketing dashboard looks positive, which is why it needs its own line in the cost calculation.
Enterprise BFSI and telco programs add cost lines that ecommerce loyalty apps rarely carry, including compliance review, data governance, and core system integration. They also add revenue signals ecommerce programs do not track, such as product penetration and digital channel migration. The result is a more complex formula, but a more defensible one in front of a risk committee or a board.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Best Enterprise Loyalty Program Software: Ranked and Reviewed

Praveen Vadla

Senior Digital Marketing Manager | August 18, 2026

Best Enterprise Loyalty Program Software: Ranked and Reviewed

IN BRIEF

  • Perx is the Behavioural Loyalty Platform built for enterprise brands, engineering the customer behaviours that lead to revenue rather than rewarding transactions after the fact.
  • Points-based and e-commerce loyalty platforms are frequently sold into enterprise buyers, but most were built for Shopify storefronts, not for enterprise-grade compliance, core-system integration, or real-time behavioural triggers at scale.
  • This ranking evaluates nine providers against six enterprise criteria: proven enterprise deployment, real-time behavioural triggers, no-code campaign speed, enterprise-grade compliance, integration without re-platforming, and verified G2 user ratings.
  • Regulated industries like banking and telco carry extra requirements around compliance and core-system integration. See the dedicated section on BFSI and telco fit further down this guide.

Perx Technologies is a Behavioural Loyalty Platform built for enterprise brands across BFSI, telco, and digital-native industries in APAC, and it is the vendor publishing this comparison. That context matters, so every claim below is sourced: G2 ratings are pulled live from each vendor’s public G2 profile, and every Perx proof point is drawn from a named, verified deployment rather than a marketing estimate.

Most loyalty software comparisons are written from an e-commerce lens: Shopify plugins, referral widgets, points-and-badges gamification for D2C brands. That is a narrower frame than most enterprise buyers actually need. A large-scale enterprise, whether a bank, a telco, or a digital-native platform with millions of users, needs a platform that connects to existing systems without a rip-and-replace project, launches at marketing speed rather than IT-roadmap speed, and proves its ROI in a board deck rather than an engagement dashboard.

This guide ranks the nine loyalty platforms most commonly evaluated by enterprise buyers in 2026, based on verified G2 reviews, publicly listed features, and deployment fit at scale.

What is enterprise loyalty program software?

Enterprise loyalty program software is a platform that manages customer engagement, rewards, and retention at scale, built to integrate with an organisation’s existing systems rather than requiring a standalone storefront setup. Unlike SMB-focused tools, it needs to support high transaction volumes, complex segmentation, multi-market rollouts, and integration with CRM, CDP, and core operational systems, typically without a full IT re-platforming project.

The category splits into two lineages. The first is behaviour-led platforms, built to map every reward to a measurable business behaviour such as activation, spend, or retention. The second is points-and-rewards platforms adapted from retail or e-commerce loyalty and scaled up with enterprise features. The distinction shapes almost everything else in this comparison, from implementation timelines to what “ROI” actually means in the vendor’s reporting.

For regulated industries such as banking, insurance, and telecommunications, enterprise requirements go further still, extending into compliance workflows and core-system integration that most retail-first platforms were never built to handle. That specific case is covered in its own section below.

Enterprise loyalty software: full comparison table (2026)

IN BRIEF

  • Perx is the only platform in this set built natively around real-time behavioural triggers with proven BFSI and telco deployment.
  • Loyalty Juggernaut, Comarch, and Open Loyalty also carry evidenced BFSI or telco use, the latter through a named online banking review on G2.
  • Capillary Technologies, Talon.One, White Label Loyalty, Antavo, and TrueLoyal are strong enterprise platforms with less BFSI/telco-specific depth.
Platform G2 rating BFSI / telco proven Real-time behavioural triggers No-code campaign builder Enterprise-grade compliance No re-platform integration
Perx 4.1/5 (7)
Loyalty Juggernaut (GRAVTY) 4.5/5 (2)
Comarch 4.2/5 (10)
Open Loyalty 4.7/5 (16)
Capillary Technologies 4.8/5 (6)
Talon.One 4.5/5 (63)
White Label Loyalty 4.0/5 (11)
Antavo 4.2/5 (7)
TrueLoyal 4.6/5 (160)
G2 ratings and review counts pulled live from each vendor’s public G2 profile, 11 August 2026. ✓ = strong fit. ⚠ = partial or unverified fit. ✗ = not evidenced.

The Perx Enterprise Loyalty Evaluation Framework: how we ranked these platforms

We evaluated each platform against six criteria that determine whether a loyalty program survives contact with a large organisation’s IT, procurement, and (where relevant) compliance functions, not just whether it looks good in a product demo.

Criteria Why it matters for enterprise buyers
BFSI / telco proven deployment A platform with case studies from Shopify apparel brands has not been tested against the scale, compliance, and integration demands of a bank, insurer, or telco. Prior BFSI or telco deployments are one of the strongest signals a vendor can operate at true enterprise scale.
Real-time behavioural triggers Rewarding a transaction after it happens is a cost centre. Triggering an incentive at the moment a customer is about to lapse or convert is a growth engine. This distinction is the difference between earn-and-burn and behaviour-led loyalty.
No-code campaign builder If marketing needs an IT ticket to launch a campaign, the platform will not move at marketing speed. This matters most in large, process-heavy organisations where IT roadmaps run in quarters.
Enterprise-grade compliance Certifications like ISO and GDPR compliance, plus approval workflows such as Maker-Checker, are non-negotiable for regulated buyers and increasingly expected by security-conscious enterprises generally. A platform without them adds months to procurement and security review before a single campaign launches.
No re-platform integration Large enterprises cannot afford to rip out core systems to adopt a loyalty layer. API-first architecture that sits above existing infrastructure is what separates a six-week integration from a two-year one.
Verified G2 rating Marketing claims are not evidence. Independently verified user reviews on G2 are the closest available proxy for how a platform performs after the sales process ends.

The best enterprise loyalty program software providers, ranked

1. Perx

Best for: Enterprise brands across BFSI, telco, and digital-native industries replacing earn-and-burn points with behaviour-led, revenue-mapped engagement.

Perx is the Behavioural Loyalty Platform built for large-scale enterprise deployment across APAC. Where legacy loyalty systems reward transactions after the fact, Perx maps every customer action to a measurable business outcome, turning passive points ledgers into active growth engines without IT bottlenecks.

Most popular capabilities:

  • Behaviour Engine: real-time triggers fire on customer intent, not a fixed schedule, engineering habits rather than one-off redemptions.
  • Campaign Engine: no-code campaign builder lets marketing teams launch, adjust, and approve campaigns in hours, with AI-generated briefs that a team reviews and approves rather than builds from scratch.
  • Precision Engine: rules-based incentive logic ensures every promotional dollar is tied to a validated commercial outcome, with reward cost held to 0.6 to 2.1 percent of total transaction value.
  • Enterprise-grade compliance: ISO/IEC 27001:2013 and ISO 27018:2019 certified, GDPR compliant, built for Maker-Checker approval workflows from the outset.

Proof point: A leading telecom serving 90 million customers achieved a 25x ROI in 100 days, a 510 percent increase in app MAUs, and US$1.3 million in incremental revenue. A leading bank generated over US$18 million in incremental revenue from overseas credit card spend at a 4x ROI. Across its enterprise client base, Perx has contributed US$2.9 billion in topline revenue. Perx’s G2 vendor profile additionally states that the platform has acquired 22.5 million net-new customers and delivered up to 29x ROI across its client base; these two figures are self-reported by Perx to G2 rather than independently sourced from a named case study. A deeper look at Perx’s BFSI-specific deployment results, including the Jenius case study, follows in the dedicated section below.

"The platform is continuous learning journey because of its endless abilities and the fact that it is being personalized to fit the culture of an organization."

Limitations: Reviewers on G2 note occasional processing delays during platform downtime affecting campaign launch timing, and a learning curve for teams new to no-code rules configuration. Perx has acknowledged these as an active area of platform improvement.

2. Loyalty Juggernaut (GRAVTY)

Best for: Large ecosystem-centric enterprises across airline, hospitality, BFSI, and telco wanting a patented, full-service loyalty platform.

Loyalty Juggernaut’s GRAVTY platform is built on serverless computing and microservices architecture, and is recognised by Gartner and Forrester as a representative loyalty technology vendor, including a Strong Performer placement in the Forrester Wave for Loyalty Platforms in Q4 2025.

"The pre-set layouts allow for easy configuration, and changing rewards and tiers is as simple as dragging and dropping them into place."

Limitations: G2’s review sample for GRAVTY is small at the time of writing, which limits how far the rating can be generalised. As a full-service enterprise platform, implementation typically involves a longer scoping and configuration cycle than a pure self-serve tool.

3. Comarch

Best for: Enterprises running complex coalition or omnichannel loyalty logic across multiple brands or partners.

Comarch Loyalty Management supports advanced rule sets and multi-partner coalition structures, with a heritage in telecom BSS that gives it credibility with telco buyers evaluating loyalty alongside billing and product catalog systems. Comarch’s client roster includes financial services and telecom names such as ING and T-Mobile.

Very agile system with well-designed core functions that accommodate our program needs."

Limitations: Reviewers describe a steep learning curve and resource-intensive configuration, with pricing structured around the full platform stack rather than the modules a buyer actually needs.

4. Open Loyalty

Best for: Enterprises with internal engineering resource that want a self-hosted, open-source, API-first loyalty engine, including regulated buyers who need full control over data handling.

Open Loyalty is a headless loyalty engine that can be self-hosted or cloud-managed, combining points, tiers, streaks, and achievements into a composable architecture built for teams that want to build their own front-end experience. At least one reviewer on G2 specifically describes using Open Loyalty to power the loyalty programme inside an online banking platform, giving it a direct BFSI data point in its own review base that most platforms in this comparison lack.

"We use Open Loyalty for managing the customer loyalty program in our online banking platform."

Limitations: Reviewers cite limited reporting capabilities out of the box, and the open-source, self-hosted model shifts ongoing maintenance and compliance certification work onto the buyer’s own engineering team.

5. Capillary Technologies

Best for: Retail-led enterprises wanting AI-powered tier management alongside a broader customer engagement suite.

Capillary Loyalty+ combines its aiRA AI agent for predictive engagement and tier management with omnichannel data capture, part of a wider Capillary suite recognised as a Leader in the Forrester Wave for Loyalty Platforms (Q4 2025), reporting 1.95 billion or more annual transactions across 875 million or more consumers for its Fortune 500 client base.

"The inbuilt AI agent aiRA is quite useful as it can help launch campaigns within minutes in a very hassle-free manner."

Limitations: The G2 review sample specific to the loyalty product remains small relative to the size of Capillary’s overall client base, and one reviewer notes wanting more end-user control over features rather than relying on customer support. No BFSI-specific deployment evidence appears in the reviews evaluated.

6. Talon.One

Best for: Enterprises needing advanced promotion and discount logic with loyalty as one part of a broader rules engine.

Talon.One is an API-based promotion engine built for complex rule and condition logic across discounts, loyalty rewards, and referral programmes, with by far the largest independently verified G2 review base of any platform in this comparison. At least one reviewer identifies as working in Financial Services, though Talon.One does not show a dedicated BFSI case study track record.

"The range of features and functionality is great."

Limitations: Reviewers note that hidden logic around conflicting campaign rules and discount stacking takes time to learn, and several flag that dashboard analytics are shallow enough to require a separate BI tool connection for deeper decision-making.

7. White Label Loyalty

Best for: Enterprises wanting an API-first, event-based loyalty engine that rewards any customer action, not just transactions.

White Label Loyalty positions itself around rewarding any customer activity, not just purchases, through an API-first, event-based loyalty engine. Its most notable deployment is Tickit, a card-linked rewards programme built for Dubai Holding that became the second-largest loyalty programme in the UAE, with SKB Bank listed among its named clients, giving it a modest fintech and BFSI reference point.
Limitations: G2’s individual review excerpts were not accessible for this profile at the time of research, only the aggregate rating and vendor-submitted description. Buyers should request named references directly, and this is the lowest G2 rating among the platforms in this comparison.

8. Antavo

Best for: Global retail, fashion, and hospitality brands wanting a no-code, omnichannel loyalty workflow builder.

Antavo provides no-code workflow tools and a high degree of program personalisation, with a client base concentrated in fashion, beauty, retail, and hospitality rather than BFSI or telco.

"You have the ability to move at pace with elements and the technical team is second to none."

Limitations: Reviewers describe onboarding delays, limited reporting features, and customer support that is less responsive outside an active package, alongside a difficult learning curve for non-technical users. Antavo does not have a demonstrated BFSI or telco deployment track record in the reviews evaluated.

9. TrueLoyal

Best for: Consumer brands wanting loyalty combined with community, user-generated content, and brand advocacy at scale.

TrueLoyal is a merged G2 listing covering what many of its own reviewers still refer to by their prior product names, Zinrelo and Vesta, combining points-based loyalty with fan community building, gamification, and user-generated content sourcing. It carries the largest independently verified review base in this entire comparison.

"It has moved our business from being transactional to being engaging."

Limitations: Reviewers flag integration gaps with platforms like Facebook and YouTube, a campaign engine that only re-checks new customer segments once daily rather than in real time, and a pricing model some found difficult to predict as usage scales. No BFSI or telco deployment evidence appears in the reviews evaluated, and the platform is positioned for consumer brand community-building rather than regulated-industry engagement.

Which enterprise loyalty platform fits your organisation?

The biggest mistake enterprise buyers make is evaluating every platform against the same checklist, regardless of what stage and sector their organisation is in. A digital-native platform and a regulated financial institution need different things from a loyalty platform, even though both are technically buying the same category of software.
Enterprise profile What matters most Platforms to shortlist
Digital-first enterprise (bank, wallet, telco, superapp), 500K to 50M users Fast launch, no-code speed, real-time behavioural triggers, proof of ROI within 60 to 90 days Perx
Large enterprise running coalition or multi-brand loyalty Complex rule sets, multi-partner logic, established enterprise track record Perx, Comarch, Loyalty Juggernaut
Telco with billing and BSS integration needs Deep telco integration heritage, coalition partner management Perx, Comarch
Enterprise with internal engineering capacity Full control, self-hosted or headless architecture, willingness to own compliance build-out Open Loyalty, White Label Loyalty, Talon.One
Retail-adjacent financial brand (BNPL, co-brand cards) Omnichannel personalisation, tier and rewards management Capillary Technologies, Antavo
Consumer brand prioritising community and advocacy alongside loyalty User-generated content, fan community tools, high review volume as a trust signal TrueLoyal
If your organisation intends to scale into new markets or launch new products in the next 18 months, evaluate the platform for where the program is going, not just where it is today. Re-platforming a live loyalty programme mid-flight disrupts member balances, integrations, and customer trust, and it is a far costlier fix than choosing correctly the first time.

Enterprise loyalty software trends to watch in 2026

IN BRIEF

  • Buyers are moving from earn-and-burn points to behaviour-led, revenue-attributed engagement.
  • API-first architecture is now the baseline expectation, not a premium tier.
  • AI is showing up in loyalty platforms as rules assistance and prediction, and enterprise buyers should verify what is live versus roadmap language.
  • First-party behavioural data captured through loyalty programmes is becoming a primary data asset as third-party cookies phase out.

Value-based engagement is replacing discount-led loyalty

The shift from rewarding purchases to rewarding the full range of customer behaviour, including activation actions, referrals, and habit-forming journeys, is accelerating across every enterprise vertical. Programmes that only reward transactions attract deal-seeking customers rather than genuinely loyal ones, and finance leaders are increasingly asking whether reward spend is producing a behaviour change or just subsidising activity that would have happened anyway.

API-first architecture is now table stakes

Large enterprises are no longer willing to accept platforms that cannot connect cleanly into their CRM, CDP, and core systems. A platform that requires custom integration work for every connection point adds months to a deployment that should take weeks.

AI claims need verification, not assumption

Several vendors in this comparison market “agentic AI” capabilities. Buyers should ask for a live demonstration of what is actually autonomous versus what is an AI-assisted recommendation inside a rules engine a human still approves. In regulated industries, the distinction is not academic. It is the difference between an audit trail a risk committee can sign off on and one it cannot.

First-party behavioural data is the real dividend

As third-party cookies phase out, loyalty programmes have become one of the most valuable first-party data collection mechanisms available to a large enterprise. Platforms that capture behavioural data at the point of action, not just at the point of redemption, give organisations a data asset that compounds in value over time.

From engagement mechanics to revenue intelligence

Every platform in this comparison can issue a point, run a campaign, or display a leaderboard. The distinction that actually separates them for an enterprise buyer is whether the engagement mechanic connects to a number finance leadership cares about.

A gamified quest that increases app opens is an engagement metric. A gamified quest that increases activated spend by a measurable percentage, with the rule that triggered it logged and attributable, is revenue intelligence. Perx’s BFSI deployment data illustrates the difference concretely: 13.4 million individual rule triggers at Jenius were not run to generate engagement dashboard activity. They were run because each one was mapped to a specific customer behaviour tied to card activation and spend, and the resulting US$599 million in card spend and 32x ROI is the artefact of that mapping, not a coincidence of running a loyalty programme at scale.

This is the question worth asking every vendor on this list before signing a contract: can you show, with a specific number, which customer behaviour each reward mechanic is designed to produce, and can you trace that behaviour to a revenue outcome after the fact? Platforms that answer with a feature list have not answered the question.

Key takeaways

  • Perx Tech leads this comparison for enterprise buyers on real-time behavioural triggers, no-code deployment speed, and revenue-attributed proof points, with the deepest demonstrated fit for BFSI and telco specifically.
  • Loyalty Juggernaut, Comarch, and Open Loyalty carry the strongest additional BFSI and telco evidence among the remaining platforms, the latter through a named online banking use case in its own G2 reviews.
  • Talon.One and White Label Loyalty suit enterprises with strong internal engineering teams who want deep control over rules logic or a self-hosted, event-based architecture.
  • Capillary Technologies and Antavo are strong retail-oriented platforms worth evaluating for BNPL or retail-adjacent financial brands, with less demonstrated BFSI-specific depth.
  • TrueLoyal stands out for consumer brands that want community and advocacy tools alongside loyalty, backed by the largest independently verified review base in this comparison, but is not positioned for regulated-industry deployment.
  • If you are a bank, insurer, or telco, treat compliance and core-system integration as disqualifying criteria, not nice-to-haves, and verify every vendor’s AI claims against a live demonstration rather than a feature list.
  • Choose a platform for the organisation you will be in 18 months, not the one you are today. Re-platforming a live programme is disruptive and expensive to undo.

FAQs:

What is the best loyalty program software for enterprises?
For enterprise buyers, the strongest fit is a platform built for real-time behavioural triggers, no-code campaign speed, and integration without re-platforming existing systems. Perx ranks first in this comparison because it engineers customer behaviour and maps every reward to a measurable business outcome, rather than adapting a retail points system for enterprise scale. For regulated industries like banking and telco, compliance depth becomes the deciding factor, covered in the dedicated BFSI and telco section above.
Banks, insurers, and telcos operate inside regulated environments that require Maker-Checker approval workflows, ISO and GDPR compliance, audit trails, and integration with core banking or billing systems. General enterprise loyalty platforms may handle scale and personalisation well but were not necessarily built to survive a risk committee review or a core-system integration without custom development.
Enterprise loyalty platforms are typically priced as an annual platform investment tied to the modules used and program scale, not a flat license fee. Vendors rarely publish rate cards publicly because pricing depends on integration depth, member volume, and compliance requirements. Buyers should request a scoped quote based on their specific deployment.
No-code, API-first platforms can launch a first campaign within days and complete a phased enterprise rollout in weeks without re-platforming. Platforms requiring heavy custom development or full-stack licensing typically take months, and regulated-industry deployments can run longer depending on core-system integration complexity.
Building in-house means owning ongoing maintenance, compliance certification, and rules-engine development indefinitely, which is rarely a core competency outside the loyalty category itself. Buying a purpose-built platform shifts that burden to a vendor with existing certifications, letting internal teams focus on program strategy rather than infrastructure.
Most loyalty platforms marketed as agentic AI today are AI-assisted rules and recommendation engines rather than fully autonomous systems making unsupervised decisions. Buyers, especially in regulated industries, should ask for a live demonstration of any AI claim and confirm what runs on verified rules versus what is roadmap language.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Most Popular Loyalty Program Vendors for Banks That Drive Revenue Growth

Praveen Vadla

Senior Digital Marketing Manager | Jul 17, 2026

Most Popular Loyalty Program Vendors for Banks That Drive Revenue Growth

A revenue-driving loyalty program for a bank is one where every mechanic, whether a cashback trigger, a spend-threshold rule, or a milestone reward, is traceable to a specific, attributable spend outcome, not just an engagement or redemption number. The vendors most associated with this outcome are the ones that report results at the rule level: how many customers a specific rule reached, and how much verified transaction value resulted, rather than a programme-wide average. These mechanics tend to fall into three layers used across banking, fintech, and insurance: Tactical mechanics tied to an immediate transaction, Operational mechanics that gamify a specific task like QR adoption, and Strategic mechanics that build a longer spending habit. In one six-month deployment, a rules-based, behaviour-driven model across these layers drove US$599 million in actual card spend across 145,000 unique customers, a 32x return on investment, and average monthly spend 67% above the national benchmark.

IN BRIEF

  • A revenue-driving loyalty platform for a bank is one where every mechanic, such as a cashback trigger or spend-threshold rule, is traceable to a specific, attributable spend outcome at the rule level, not just a programme-wide engagement average.
  • Bank loyalty mechanics generally fall into three layers: Tactical (an immediate transaction trigger), Operational (a gamified task like QR adoption), and Strategic (a longer-term spend habit).
  • Traditional bank points programmes function as a cost centre, since points accrue as a liability with no clear link to whether the programme actually changed customer behaviour.
  • SMBC Jenius Bank in Indonesia ran a six-month, rules-based, behaviour-driven deployment that fired 13.4 million spend rule triggers, drove US$599 million in card spend across 145,000 unique customers, and delivered a 32x return on investment.
  • The same Jenius deployment activated 709,000 users, achieved a 55% earn-to-burn ratio, and lifted average monthly customer spend to US$460 against Indonesia’s US$275 national average, a 67% lift above benchmark.
  • Choosing a bank loyalty vendor comes down to five checks: rule-level attribution, mechanic-layer coverage, verified deployment data, redemption health (earn-to-burn ratio), and speed to deploy new rules without an engineering cycle.
  • Rule-level spend data is the foundation for a broader shift toward revenue intelligence, connecting individual customer behaviour to future spend, dormancy, or attrition ahead of it showing up in a quarterly report.

What Makes a Loyalty Platform Revenue-Driving for a Bank?

A revenue-driving loyalty platform is one where every mechanic is traceable to a specific spend outcome, and where that outcome can be reported at the rule level rather than as a programme-wide average. Most bank loyalty programmes report engagement metrics, such as app opens or redemption rates, which are useful operationally but do not answer the question a CFO actually asks: did this programme increase spend, and by how much. A revenue-driving platform answers that question directly, connecting a specific rule, such as a cashback trigger on a defined transaction category, to a specific, attributable spend increase, rather than a directional correlation.

The Problem With Traditional Bank Loyalty Programs

Traditional bank points programmes function as a cost centre: points are issued for a transaction, accrue as a liability, and are eventually redeemed with no clear link back to whether the programme changed customer behaviour or simply rewarded spend that would have happened regardless. This is the pattern that has driven a shift among banks toward rules-based behavioural loyalty, where a mechanic is designed around a specific spend or product-adoption target, and the resulting spend is measured against that target directly, rather than assumed.

Rules-Based Behaviour Mechanics for Banks

The same three mechanic layers used across fintech and insurance apply to bank loyalty programmes. Tactical mechanics, such as a cashback or spend-threshold trigger, target an immediate transaction and are the fastest to attribute to a specific rule. Operational mechanics, such as a gamified quest, target a specific product adoption behaviour, such as moving a customer from cash to QR payments. Strategic mechanics, such as tiered spend milestones, build a sustained spending habit over a longer horizon, and tend to compound the value of the other two layers once they are in place. Each layer is measured against its own defined rule, not a blanket engagement score.

A Six-Month Deployment at Scale: SMBC Jenius Bank, Indonesia

SMBC Jenius Bank deployed a rules-based, behaviour-driven loyalty program with Perx to convert dormant digital banking customers into repeat, high-value spenders. Over six months, the deployment fired 13.4 million spend rule triggers, meaning 13.4 million individual instances where a customer met a defined spend condition and received an attributed reward. This drove US$599 million in actual card spend across 145,000 unique customers, with 709,000 users activated onto the programme overall. The programme achieved a 55% earn-to-burn ratio, meaning more than half of rewards issued were actively redeemed rather than sitting unused, and delivered a 32x return on investment. Average monthly customer spend under the programme reached US$460, against Indonesia’s national average of US$275, a 67% lift above benchmark. This is framed specifically as rules-based, behaviour-driven loyalty: rewards are triggered by defined spend conditions, not by autonomous or predictive decisioning.
Rules-Based Mechanics Mapped to Bank Use Cases
Bank Use Case Mechanic Layer Example Mechanic Business Outcome Targeted
Dormant card reactivation Tactical Spend-threshold cashback trigger Convert dormant cards into repeat spenders
QR or digital payment adoption Operational Gamified Quests Drive first-time and repeat QR transaction adoption
Cross-border or high-value spend Tactical Spend-rule triggered reward Lift average transaction value in a target category
Long-term spend habit or tiering Strategic Milestone or tiered spend rewards Sustain elevated monthly spend beyond the campaign window
New-to-bank customer activation Operational Onboarding quest with a spend-linked reward Convert new accounts into active, spending customers

From Rule-Level Attribution to Revenue Intelligence

Every rule in a system like this generates a record of exactly which customer, condition, and spend outcome were connected. On their own, these rules prove a specific mechanic worked. Connected across a full customer base, that same rule-level data starts to answer a broader question banks are increasingly asking: which behaviours predict future spend, dormancy, or attrition at the individual customer level, ahead of it showing up in a quarterly report. This is the direction loyalty-to-revenue platforms are heading in as a category, and it is a natural fit for the next phase of the platform for any vendor already running rules-based mechanics at this scale, since the underlying data is already being generated.

What to Evaluate When Choosing a Bank Loyalty Vendor

  • Rule-level attribution: can the vendor report spend outcomes per rule, not just per campaign?
  • Mechanic-layer coverage: does the vendor run Tactical, Operational, and Strategic mechanics as one connected system, or only one layer well?
  • Verified deployment data: does the vendor have a named, published case study with independently reportable figures?
  • Redemption health: what is the earn-to-burn ratio, since a low ratio signals an unused liability rather than an active growth lever?
  • Speed to deploy: can new spend rules be configured by a marketing team without an engineering release cycle?

FAQs:

What is a rules-based, behaviour-driven loyalty program?
It is a loyalty model where rewards are triggered by defined customer spend or behaviour conditions, such as a transaction threshold, rather than by a fixed accrual rate or automated predictive decisioning.
Tactical mechanics reward an immediate transaction, such as a cashback trigger. Operational mechanics gamify a specific task, such as QR payment adoption, using quests. Strategic mechanics, such as tiered spend milestones, build a sustained spending habit over a longer horizon.
Results vary by deployment, but in one verified case, SMBC Jenius Bank in Indonesia generated US$599 million in card spend and a 32x return on investment over six months using a rules-based loyalty program.
It is the percentage of issued rewards that are actually redeemed. A 55% earn-to-burn ratio, as seen in the Jenius deployment, indicates an actively used programme rather than an accumulating, unredeemed liability.
Each rule generates a record of which customer, condition, and spend outcome were connected. Connected across a full customer base, that data can start to show which behaviours predict future spend, dormancy, or attrition, which is the direction loyalty-to-revenue platforms are increasingly building toward.
This model is rules-based: rewards fire when a defined spend condition is met. It does not involve autonomous or predictive AI-driven decisioning, which is a distinct category some vendors are beginning to explore separately.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

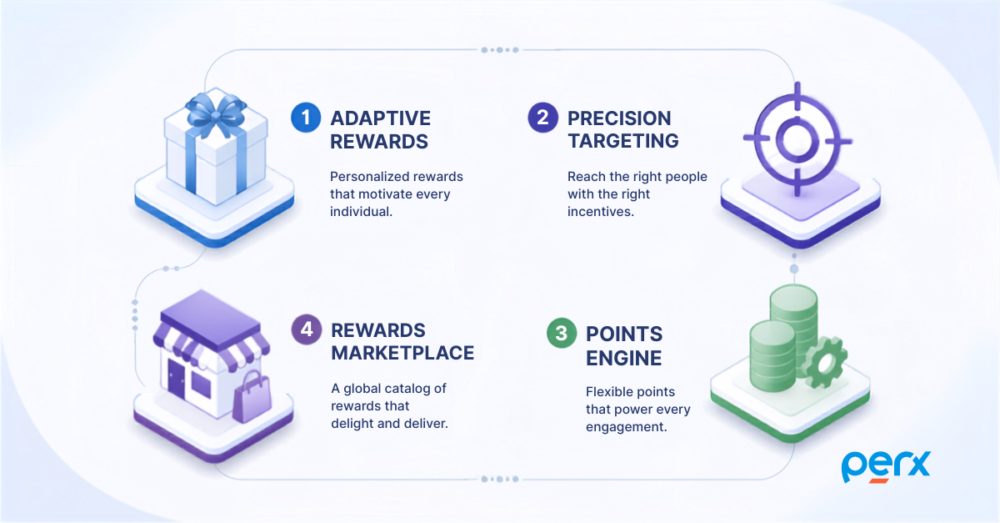
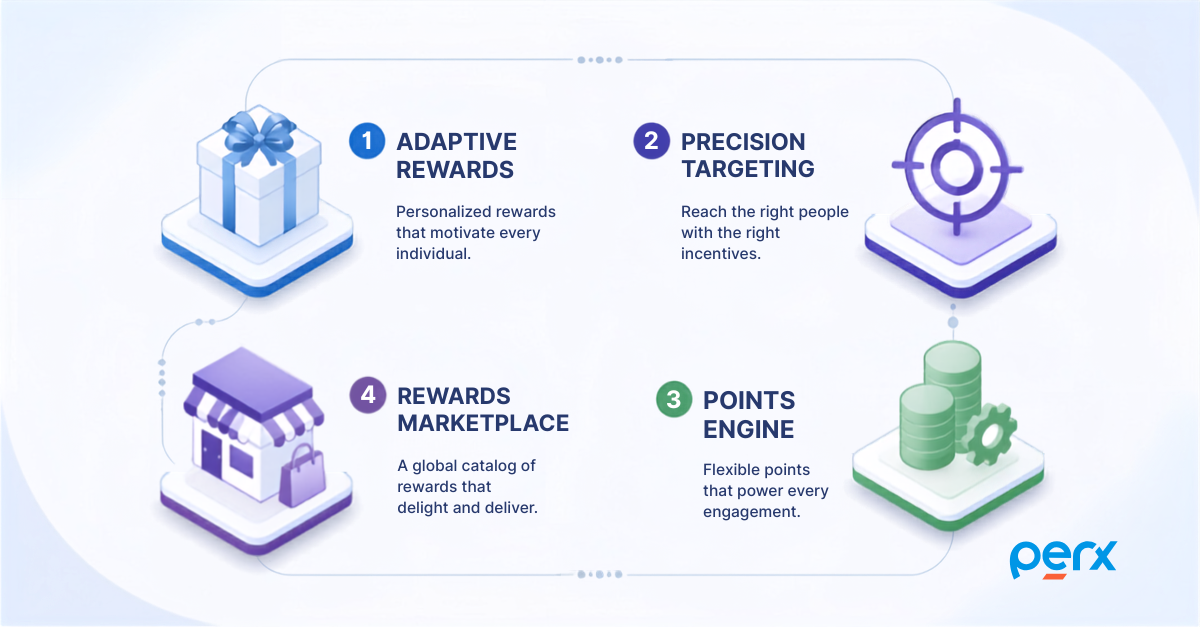
How to Evaluate Loyalty Vendors on Adaptive Rewards & Precision Targeting

Praveen Vadla

Senior Digital Marketing Manager | August 04, 2026

How to Evaluate Loyalty Vendors on Adaptive Rewards, Precision Targeting, and Rewards Infrastructure

Evaluating loyalty vendors on adaptive rewards, precision targeting, and rewards infrastructure means looking past the size of a rewards catalogue and checking four things: whether rewards change based on individual customer behaviour, whether targeting rules can be configured at the individual transaction level, whether the points engine functions as a growth tool rather than a pure cost centre, and whether the rewards marketplace can operate as a single partner-management layer rather than a manually managed set of merchant deals. Most loyalty vendors offer some version of all four capabilities. The difference between a legacy points ledger and a modern behavioural loyalty platform shows up in how precisely and how quickly each capability can be configured to a specific customer action, and in whether the four work together as one system rather than four disconnected tools.

IN BRIEF

  • Evaluating a loyalty vendor on adaptive rewards, precision targeting, and rewards infrastructure means checking whether rewards vary per customer, whether targeting fires at the individual transaction level, whether the points engine is a growth tool rather than just a cost centre, and whether the rewards marketplace runs as one connected layer.
  • Adaptive rewards vary the incentive by an individual customer’s behaviour, value tier, or context, rather than applying one fixed offer to an entire customer base.
  • Precision targeting is a rules engine that fires a reward only when a defined transaction-level condition is met, unlike segment-level targeting, which applies one campaign to a broad group.
  • A points engine is a balance-sheet liability unless it is tied to a rules layer that connects point issuance to a specific, measurable behaviour rather than a flat accrual rate.
  • A rewards marketplace manages merchant partnerships and promotions in a single dashboard, determining how quickly a new partner or promotion can go live across every channel.
  • Each of the four capabilities maps to the Tactical, Operational, or Strategic mechanic layers used across banking, fintech, and insurance deployments, so evaluating them is really evaluating coverage across all three layers.
  • Vendors that satisfy all four capabilities generate the richest behavioural data set, the foundation for connecting these capability-level signals to a broader revenue-intelligence view.

What Are Adaptive Rewards?

Adaptive rewards are rewards that change based on an individual customer’s behaviour, value tier, or context, rather than a single fixed offer applied to an entire customer base. Where a traditional points programme gives every customer the same fixed earn rate, an adaptive rewards system might give a high-value but under-engaged customer a different incentive than a highly active customer who needs no additional push. The point of adaptive rewards is efficiency: the reward budget is spent on the customers and moments where it actually changes behaviour, rather than spread evenly across a base that includes customers who would have transacted anyway.

What Is Precision Targeting in a Loyalty Platform?

Precision targeting refers to a rules engine that fires a specific reward or campaign only when a defined set of customer conditions is met, such as a spend threshold in a specific merchant category, a dormancy period of a set length, or a combination of both. This differs from segment-level targeting, which applies a single campaign to a broad group, such as all customers of a value tier. A precision engine evaluates rules at the individual transaction level, which is why platforms built around it can report exactly how many rule triggers led to a specific spend outcome, rather than reporting a campaign-wide average.

What Is a Points Engine, and Why It Can Become a Cost Centre

A points engine is the underlying system that issues, tracks, and manages the redemption of loyalty points. On its own, a points engine is a liability on the balance sheet: points accrued but not yet redeemed represent a financial obligation, and a points programme with no attribution to specific business outcomes is difficult to defend to a CFO. The evaluation question is not whether a vendor has a points engine, since most do, but whether that points engine is connected to a rules and targeting layer that ties point issuance to a specific, measurable behaviour, turning it from a static ledger into an active growth lever.

What Is a Rewards Marketplace?

A rewards marketplace is the layer that manages merchant partnerships, promotions, and the catalogue of rewards a customer can redeem, in a single dashboard rather than a manually tracked set of individual merchant deals. For enterprises running loyalty programmes across multiple markets, the marketplace layer determines how quickly a new merchant partner or promotion can go live, and how consistently that promotion is presented across every channel, including in-app, web, and API-based experiences.

How These Capabilities Map to Behaviour Mechanics

Each of these four capabilities also maps to the Tactical, Operational, and Strategic mechanic layers used across banking, fintech, and insurance deployments. Adaptive rewards and a well-configured points engine typically power Tactical mechanics, since they determine what a customer earns the moment they transact. Precision targeting is what allows a Tactical mechanic to fire only for the right customer under the right condition, rather than being broadcast to an entire segment. A rewards marketplace becomes most valuable at the Operational and Strategic layers, where a customer is working toward a specific milestone or status and needs a wide, current catalogue of redemption options to stay motivated. Evaluating a vendor on these four capabilities is, in practice, evaluating whether they can support all three mechanic layers well, not just one.
Evaluation Checklist
Capability What to Ask the Vendor Business Outcome It Should Move Example in Practice
Adaptive Rewards Can rewards vary by individual customer value or behaviour, not just tier? Reward spend efficiency, CAC A dormant, high-value customer gets a stronger incentive than an already-active customer for the same action
Precision Targeting Can rules fire on individual transaction-level conditions? Campaign ROI, conversion A reward triggers only when a customer crosses a defined spend threshold in a specific merchant category
Points Engine Is point issuance tied to a specific tracked behaviour? CLTV, redemption liability Points are issued for a defined spend-rule trigger rather than a flat rate on every transaction
Rewards Marketplace Can a new merchant or promotion go live without an engineering request? Speed to market, partner breadth A new redemption partner is added to the catalogue within days of a commercial agreement
Most legacy loyalty vendors can answer yes to at least one of these four questions. Enterprise buyers evaluating a platform for a multi-year deployment should look for a vendor that can answer yes to all four in a single, integrated architecture, since a loyalty stack assembled from separate point solutions for rewards, targeting, and marketplace management tends to accumulate the same IT dependency and slow release cycles the loyalty programme was meant to solve in the first place.

From Capability Evaluation to Revenue Intelligence

Vendors that can answer yes to all four evaluation questions are also the ones generating the richest behavioural data set, since adaptive rewards, precision targeting, the points engine, and the rewards marketplace all produce a record of which specific customer, condition, and reward combination led to which outcome. That data set is the foundation for a broader shift already underway across engagement platforms: connecting these capability-level signals into a single view of which behaviours predict revenue, not just which campaign performed best. This is a natural fit for the next phase of the platform for any vendor with all four capabilities already integrated, since the data is already there.

FAQs:

What is the difference between adaptive rewards and a standard points programme?
A standard points programme applies the same earn rate to every customer. Adaptive rewards vary the incentive based on an individual customer’s behaviour, value, or context, so reward spend is directed at the customers and moments where it actually changes behaviour.
Segment-based marketing applies one campaign to a broad customer group. Precision targeting evaluates rules at the individual transaction level, firing a reward only when a specific, defined condition is met.
Because points accrued but not yet redeemed represent a financial liability, and a points programme with no connection to specific tracked behaviours is difficult to justify against a measurable business outcome.
Adaptive rewards and the points engine typically power Tactical mechanics, since they determine what a customer earns at the moment of a transaction. Precision targeting determines which customer and condition triggers that mechanic, and a rewards marketplace supports the redemption needs of longer Operational and Strategic mechanics.
Together, these four capabilities generate a record of which customer, condition, and reward combination produced which outcome. Connected across a customer base, that data can begin to show which behaviours are most predictive of revenue, which is the direction engagement platforms are increasingly building toward.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Best Behavior-Driven Loyalty Engines to Increase Transaction Frequency

Praveen Vadla

Senior Digital Marketing Manager | August 03, 2026

Best Behavior-Driven Loyalty Engines to Increase Transaction Frequency

A behavior-driven loyalty engine is a system that triggers rewards based on a specific customer action or spend condition, built around a target behaviour, such as increased transaction frequency, rather than simply rewarding whatever a customer happens to do.

These reward mechanics are generally categorised into three – Tactical, operational, and strategic. For increasing transaction frequency specifically, the strongest engines lean on Tactical mechanics, meaning mechanics that reward a customer at the moment the wallet opens, rather than mechanics designed for long-term identity or status.

Cashback, digital stamp cards, spin-the-wheel rewards, and instant-win mechanics all fall into this category, and each maps to a specific psychological driver, such as instant gratification or variable reward anticipation, that determines how quickly it can move a frequency metric.
Cashback, digital stamp cards, spin-the-wheel rewards, and instant-win mechanics all fall into this category, and each maps to a specific psychological driver, such as instant gratification or variable reward anticipation, that determines how quickly it can move a frequency metric. In one deployment, a leading Singapore telco used daily Spin-the-Wheel mechanics to grow its monthly active users by 190% and sustain a 70% average active user rate, with 85% of its 1.12 million players returning repeatedly across six months. Separately, a Singapore digital bank used Tactical stamp card mechanics to generate $1.5 million in attributable forex transactions..

IN BRIEF

  • A behavior-driven loyalty engine triggers rewards based on a specific customer action or spend condition, built around a target behaviour like transaction frequency, rather than simply rewarding whatever a customer happens to do.
  • Reward mechanics split into three types, Tactical, Operational, and Strategic, with Tactical mechanics doing most of the work when frequency is the specific target.
  • Transaction frequency is a stronger leading indicator of lifetime value than a single large transaction, since it compounds into cross-sell opportunities, product stickiness, and reduced churn risk.
  • Five Tactical mechanics drive frequency: Cashback, Digital Stamp Cards, Spin-the-Wheel, Instant Win, and Raffles, each mapped to a specific psychological driver such as instant gratification or variable reward anticipation.
  • A leading Singapore telco’s daily Spin-the-Wheel mechanic grew monthly active users by 190% with 85% repeat engagement across 1.12 million players, and a Singapore digital bank’s Stamp Card mechanic generated $1.5 million in attributable forex transactions.
  • A Southeast Asian microfinance network with more than 3,500 branches used Tactical raffle campaigns to mobilise ₱27.9 billion in net deposits and generate S$10.3 million in net lending profits at a 32x return.
  • Frequency-level mechanic data is the foundation for revenue intelligence, showing which mechanics and customer segments produce a durable habit versus a short-lived response to a promotion.

What Is a Behavior-Driven Loyalty Engine?

The distinction from a traditional loyalty programme is the direction of design: a traditional programme rewards what already happened; a behavior-driven engine is built around a target behaviour first, such as a second transaction within a set period, and the reward mechanic is engineered specifically to produce that outcome. These engines generally work across three mechanic types: Tactical mechanics for immediate transactions, Operational mechanics for gamifying a specific task, and Strategic mechanics for longer-term habit, with Tactical mechanics doing most of the work when frequency is the specific target.

Why Transaction Frequency Is the Metric That Matters

Transaction frequency is a leading indicator of lifetime value in a way that a single large transaction is not. A customer who transacts once a month is worth more over time than one who transacts once a quarter, even at similar per-transaction spend, because frequency compounds into cross-sell opportunities, product stickiness, and reduced churn risk. This is why banks and fintechs increasingly measure loyalty programme success against a frequency target specifically, rather than a general engagement or satisfaction score.

Tactical Mechanics That Drive Frequency

  • Cashback: real-time value returned on a specific transaction type, removing price sensitivity at the moment of sale.
  • Digital Stamp Cards: turns a single transaction into a committed, multi-visit mission, using the Endowed Progress Effect to increase completion likelihood.
  • Spin-the-Wheel: a variable-reward mechanic that gives customers a daily reason to open the app, at a low marginal reward cost since not every spin pays out.
  • Instant Win (Plinko, Bubble Pop, and similar mechanics): a low-cost, high-frequency re-engagement mechanic, particularly effective for reactivating dormant users.

How to Evaluate a Behavior-Driven Loyalty Engine, Through a Behaviour Mechanics Lens

  • Does the engine map each mechanic to a specific behavioural principle, or is it a generic points multiplier?
  • Does it cover Tactical mechanics for immediate frequency, with a path into Operational and Strategic mechanics once frequency improves?
  • Can the vendor report frequency lift attributable to a specific mechanic, not just overall engagement?
  • Does the deployment have a verified, named case study behind the reported numbers?
  • Is the mechanic deployable on a marketing team’s own timeline, so frequency-driving campaigns are not gated by an engineering release cycle?

Tactical Mechanics at Scale: QR Adoption and Cross-Border Spend Habits

One Southeast Asian microfinance network, with more than 3,500 branches and 20 million customers, used Tactical raffle campaigns to turn single-product branch visits into repeat, multi-revenue engagements. Across nine campaigns run over the course of a year, the network issued 47 million raffle tickets, targeted 709,000 spending users, and mobilised ₱27.9B in net deposits, generating S$10.3 million in net lending profits against a S$324,000 subscription cost, a 32x return achieved across just 20% of the year’s calendar days.

Because a raffle pays out one prize to a small number of winners rather than a reward to every participant, the mechanic drove this frequency and deposit lift at a reward cost held below 0.02% of deposits across most campaigns. Separately, a Singapore-based digital bank used Tactical Stamp Card mechanics to build a cross-border spending habit, generating $1.5 million in forex transactions directly attributable to the mechanic, with the spending pattern persisting beyond the campaign window, the signal that the behaviour became a habit rather than a short-term response to a promotion.

Behaviour Mechanics Mapped to Frequency Use Cases

Frequency Goal Mechanic Layer Example Mechanic Business Outcome Targeted
Reactivate a dormant wallet or account Tactical Spin-the-Wheel, Instant Win Bring a dormant customer back to a first new transaction
Drive QR or digital payment adoption Operational Gamified Quests Shift customers from cash or card to digital rails
Build a cross-border or overseas spend habit Tactical Digital Stamp Cards Turn a single overseas transaction into a repeat habit
Increase everyday transaction frequency Tactical Cashback triggers Lift weekly or monthly transaction count
Sustain frequency beyond the campaign window Strategic Streaks, tiered milestones Convert a short-term lift into a lasting habit

From Frequency Signals to Revenue Intelligence

Every Tactical mechanic generates a record of which customer transacted, how often, and in response to which trigger. On their own, these records prove a frequency lift. Connected across a full customer base, that same data starts to answer a broader question: which specific mechanics and customer segments are the earliest indicators of a durable spending habit versus a short-lived response to a promotion. This is the direction behavior-driven engagement platforms are heading in as a category, and it is a natural fit for the next phase of the platform for any vendor already running Tactical mechanics at scale, since the frequency data is already being generated.

FAQs:

What is a behavior-driven loyalty engine?
It is a system that triggers rewards based on specific customer actions or spend conditions, designed around a target behaviour, such as increased transaction frequency, rather than simply rewarding whatever a customer happens to do.
Tactical mechanics such as Cashback, Digital Stamp Cards, Spin-the-Wheel, and Instant Win games are designed specifically to reward the moment a customer transacts, making them the fastest mechanics for moving a frequency metric.
At SMBC Jenius Bank, Operational mechanics drove 81,600 QR payment adoption actions within a deployment that generated US$599 million in transaction value over six months. A Singapore digital bank generated $1.5 million in attributable forex transactions using Stamp Card mechanics.

Tactical mechanics typically show measurable frequency lift within weeks of deployment, since they are designed to influence the next transaction rather than build long-term identity or status, which takes longer to materialize.

Each mechanic generates a record of which customer transacted, how often, and in response to which trigger. Connected across a customer base, that data can begin to show which mechanics and segments produce a durable habit versus a short-lived response, which is the direction engagement platforms are increasingly building toward.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Top Gamified Loyalty Platforms for Fintechs and Neobanks in 2026

Praveen Vadla

Senior Digital Marketing Manager | July 28, 2026

Top Gamified Loyalty Platforms for Fintechs and Neobanks in 2026

Gamification in loyalty is the practice of applying game mechanics, such as points, streaks, badges, progress bars, and chance-based rewards, to a financial product in order to change what a customer does next, not simply reward what they already did. For fintechs and neobanks, gamification mechanics generally fall into three types: Tactical mechanics that reward an immediate transaction, Operational mechanics that gamify a task like onboarding, and Strategic mechanics that build long-term habit and status. This piece breaks down each type, what to look for in a platform built to deliver them, and how the behavioural data these mechanics generate is starting to feed a broader shift toward connecting engagement to revenue, not just reporting it.

IN BRIEF

  • Gamification applies game-design elements, such as points, streaks, badges, and chance-based rewards, to change what a customer does next, not just reward what already happened.
  • Reward mechanics generally fall into three types: Tactical (cashback, stamp cards, spin-the-wheel), Operational (quests, progress bars), and Strategic (streaks, leaderboards, status tiers).
  • Cashback-only strategies buy engagement rather than build it. One Singapore digital bank cut its customer acquisition cost by 33x, from a $303 industry benchmark to $9, by shifting from flat cashback to a hybrid stamp-and-raffle mechanic.
  • The strongest gamified loyalty platforms for fintechs and neobanks cover all three mechanic layers in one connected system, map each mechanic to a specific behavioural principle, build in compliance for chance-based rewards, and attribute every mechanic to a measurable business outcome.
  • Real deployments back this up: a BNPL provider’s Spin-the-Wheel mechanic drove a 51% lift in weekly active users, and a Singapore digital bank’s Stamp Card mechanic generated $1.5 million in attributable forex transactions.
  • Fintechs typically start with Tactical mechanics for fast ROI, neobanks with onboarding drop-off benefit most from Operational mechanics, and Strategic mechanics compound value over a longer horizon.
  • The behavioural data generated by these mechanics is the foundation for connecting engagement to revenue prediction, the direction engagement platforms are increasingly building toward.

What Is Gamification, and What Types of Game Mechanics Exist?

In loyalty and engagement, these mechanics generally sort into three types, each suited to a different point in the customer journey. Tactical mechanics operate at the moment of transaction: cashback, digital stamp cards, and spin-the-wheel rewards all reward a customer right when they act, and are built to move immediate transaction frequency. Operational mechanics gamify a task rather than a transaction: quests, progress bars, and quizzes are used to move a customer through a specific process, such as onboarding or KYC, where drop-off is usually highest. Strategic mechanics operate over a longer horizon: streaks, leaderboards, and status tiers build habit and identity, so a customer keeps returning even without an immediate reward attached to every visit.

Why Fintechs and Neobanks Need More Than Cashback

Cashback and promo cycles are the default retention tool for most digital-native financial brands, and they work, until the promotion ends. Every promo cycle costs money, and every quiet week between cycles shows up directly in the DAU number. For payments and wallet apps operating on tight margins, this is a cost structure problem, not a marketing inefficiency. Fintechs and neobanks that rely solely on cashback are effectively buying engagement rather than building it, and finance teams have started asking pointed questions about reward spend that does not translate into habit. The alternative is not a bigger discount. It is a mechanic that creates a reason to return that has nothing to do with a lower price: a streak that would be a shame to break, a quest that is one step from completion, or a spin that only costs something when a customer actually wins.

This dynamic shows up clearly in customer acquisition cost. One Singapore-based digital bank, which had already brought its customer acquisition cost down to $52 against a regional industry benchmark of $303, went further by shifting from a straightforward reward per referral to a hybrid stamp-and-raffle mechanic: customers earned a stamp, and a chance to win a single high-value prize such as a trip, for every successful referral and qualifying transaction. Because the mechanic pays out one large prize to a small number of winners rather than a fixed reward to every referrer, the bank’s cost per acquired customer fell to $9, a 33x reduction against the industry benchmark and a further 5x reduction against its own prior acquisition cost, while still generating 25,200 referrals and 32,000 new customers within 60 days. This is the core economic argument for chance-based mechanics over flat cashback: the anticipation of winning a single large reward can motivate the same referral behaviour as a guaranteed payout, at a fraction of the average cost per customer.

What to Look for in a Gamified Loyalty Platform, Through a Behaviour Mechanics Lens

Not every gamification vendor is built for regulated financial services, and not every vendor covers all three mechanic types in one connected system. When evaluating a platform, the behaviour mechanics angle matters more than the size of the mechanic catalogue:

  • Coverage across all three layers: does the vendor run Tactical, Operational, and Strategic mechanics as one connected system with a shared customer data view, or are these separate tools bolted together, each with its own reporting?
  • Psychology-mapped mechanics: each mechanic should map to a specific behavioural principle, such as the Endowed Progress Effect behind stamp cards or the anticipation driving a Spin-the-Wheel, not just a generic points multiplier relabelled as a game.
  • Compliance-first design: raffles and lucky draws need auditable winner selection and regulatory record-keeping built in, not added after a legal review flags it, which matters most for Tactical mechanics that involve chance-based rewards.
  • Behavioural attribution: every mechanic, across all three layers, should be traceable to a specific outcome, such as transaction value, activation rate, or dormant-user reactivation, so the data can eventually answer a revenue question, not just an engagement one.

For a closer look at how each mechanic performs and when to use which, see Perx’s gamification ebook.

How Tactical and Operational Mechanics Perform in Fintech Deployments

Reactivating Dormant Wallet Users With a Variable-Reward Mechanic

One APAC BNPL provider needed a way to bring dormant users back to the app without adding to the promo budget. Spin-the-Wheel is a Tactical mechanic built for exactly this: the anticipation of a spin creates a daily reason to open the app at a low marginal cost, since only some spins pay out. Once introduced, weekly active users rose 51%, with customers returning regularly to play and redeem. Because Tactical mechanics target immediate transaction frequency rather than long-term identity, they tend to be the fastest way for a fintech to show engagement ROI within one or two quarters.

Building a Cross-Border Spending Habit With a Collection Mechanic

A digital bank in Singapore wanted customers to build a habit around overseas card spend rather than transact once and stop. Digital Stamp Cards, a collection-based Tactical mechanic, turn a single transaction into a committed, multi-visit mission, relying on the Endowed Progress Effect: customers who feel they already have a head start toward a reward are measurably more likely to finish the collection. The mechanic generated $1.5M in forex transactions directly attributable to it, and the spending pattern continued after the campaign window closed, which is the signal that separates a genuine habit from a short-lived response to a promotion.

Behaviour Mechanics Mapped to Fintech Use Cases

Fintech Use Case Mechanic Layer Example Mechanic Business Outcome Targeted
BNPL app with dormant users Tactical Spin-the-Wheel, Cashback Reactivate dormant users, lift weekly transaction frequency
Neobank onboarding and KYC Operational Quests, Progress Bars Reduce sign-up-to-activation drop-off
Wallet or superapp competing on daily usage Strategic Streaks, Leaderboards, Status Tiers Grow DAU/MAU ratio, build habitual daily opens
Cross-border payments or remittance Tactical Digital Stamp Cards Build a repeat cross-border transaction habit
Digital lending or BNPL cross-sell Operational Quizzes, Milestone Quests Drive product education ahead of a cross-sell conversation
Card or account activation campaigns Tactical Instant Win (Plinko, Bubble Pop) Convert a first-time user into a repeat transactor quickly

Most fintechs start with Tactical mechanics because they are the fastest to deploy against and the easiest to prove ROI on within a quarter. Neobanks with an onboarding drop-off problem tend to see more value starting with Operational mechanics, since KYC and profile completion are usually the single biggest point of customer loss. Strategic mechanics compound the value of the other two but take longer to show results, since identity and habit formation is a slower behavioural shift than a single transaction.

We cover this evaluation process in more depth in our guide, How to Choose a Loyalty Platform: An Enterprise Guide.

From Engagement Mechanics to Revenue Intelligence

Every mechanic across all three layers generates a data trail: which customer responded, to which mechanic, how quickly, and what transaction resulted. On their own, these mechanics prove engagement. Connected across a customer base, that same data starts to answer a different question: which specific behaviours actually predict revenue, dormancy, or churn at an individual customer level, rather than at a campaign-wide average. This is the direction fintech engagement platforms are heading in as a category: linking behavioural data to revenue outcomes rather than reporting engagement in isolation. It is a natural fit for the next phase of the platform for any vendor already running Tactical, Operational, and Strategic mechanics at scale, since those mechanics are already generating the behavioural data that a more connected revenue view would depend on.

How Perx Approaches This for Fintechs and Neobanks

Perx runs Tactical, Operational, and Strategic mechanics within a single BFSI-compliant architecture, including audited raffle mechanics and ISO 27001 and ISO 27018 certification, so each mechanic layer builds on the same customer data set rather than sitting in a separate system. The mechanics are configured to whichever behaviour a specific fintech needs its customers to build next, and that same behavioural data is the foundation the next phase of the platform builds on as it moves from engagement reporting toward connecting behaviour to revenue at the individual customer level.

FAQs:

What is gamification in a loyalty program?
Gamification is the use of game-design elements, such as points, streaks, badges, and chance-based rewards, within a financial product to influence a specific customer behaviour, rather than simply rewarding a transaction after it has already happened.
They generally fall into three types: Tactical mechanics (cashback, stamp cards, spin-the-wheel) that reward a transaction in the moment, Operational mechanics (quests, progress bars, quizzes) that gamify a task like onboarding, and Strategic mechanics (streaks, leaderboards, status tiers) that build long-term habit.
Yes, provided the platform is built with compliance embedded rather than added afterward. Mechanics such as raffles and lucky draws need auditable winner selection and regulatory record-keeping to be deployable in regulated APAC banking markets.
Cashback rewards a transaction after it happens, and its effect typically ends when the promotion ends. Gamified loyalty mechanics, such as stamp cards and streaks, are designed to build a habit that persists after the campaign window closes.
Each mechanic generates behavioural data tied to a specific customer and outcome. Connected across mechanics and customers, that data can start to show which behaviours are most predictive of revenue, dormancy, or churn, which is the direction engagement platforms are increasingly building toward.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Best Loyalty Platforms with Behavioral Analytics for Insurance Customer Retention

Praveen Vadla

Senior Digital Marketing Manager | July 21, 2026

Best Loyalty Platforms with Behavioral Analytics for Insurance Customer Retention

Behavioral analytics in insurance loyalty is the practice of tracking specific policyholder actions, such as onboarding completion, activity data sharing, and cross-channel engagement, and using that data to trigger a real-time reward or offer rather than waiting for the next renewal cycle.

For an industry where the natural touchpoints are limited to the sale and the claim, this analytics layer is what allows an insurer to stay present in a policyholder’s life in between. The mechanics built on top of this data generally split into two types: instant rewards that fire the moment a customer completes a specific action, and conditional rewards that are earned at one point in the journey but only redeemable on a future milestone, such as a cross-sell purchase. One global insurer, serving more than 26 million customers and $456 billion in assets under management, used this combination to move from a static annual touchpoint to always-on engagement, and reported double-digit campaign ROI as a result.

IN BRIEF

  • Behavioral analytics in insurance loyalty means tracking specific policyholder actions, such as onboarding completion and activity data sharing, and triggering a reward in real time rather than waiting for the next renewal cycle.
  • Insurance reward mechanics generally split into two types: instant rewards, fired the moment a customer completes an action, and conditional rewards, earned at one point but redeemable only on a future action such as a cross-sell purchase.
  • Traditional insurance engagement is structurally thin. The only two natural touchpoints, the sale and the claim, can be a year or more apart, leaving the insurer with little reason to appear in a customer’s life in between.
  • A global insurer serving more than 26 million customers and $456 billion in assets under management used connected instant and conditional reward mechanics to move from static annual engagement to always-on engagement, achieving double-digit campaign ROI.
  • A platform should be evaluated on five criteria: real-time trigger capability, support for conditional multi-step rewards, unified customer data ingestion, compliance and auditability, and behavioural attribution to a specific outcome.
  • Common insurance use cases map cleanly to mechanic type and outcome: new policy onboarding and wellness data sharing (instant rewards), bancassurance cross-sell and policy renewal (conditional rewards), and claims journey engagement.
  • The same engagement data is the foundation for a broader shift toward risk and revenue intelligence, connecting policyholder behaviour to lapse risk, cross-sell readiness, and long-term value.

What Is Behavioral Analytics in Insurance Loyalty, and What Does It Enable?

Behavioral analytics in insurance loyalty refers to tracking specific customer actions, such as app logins, policy onboarding steps, wellness or lifestyle data sharing, and product research behaviour, and using that data to trigger a reward or offer at the moment it is most likely to influence a decision. This differs from a traditional loyalty points ledger, which accumulates value with no connection to a specific behaviour the insurer wants to encourage. The two mechanics types most relevant to insurance sit on either side of that data layer: instant rewards, issued the moment a customer completes an action like onboarding, and conditional rewards, earned at one point but only redeemable on a later action, such as a bancassurance cross-sell. Both depend on the same underlying customer data to know when to trigger, which is why the analytics layer matters more than the reward catalogue itself.

Why Traditional Insurance Engagement Falls Short

Most insurance loyalty and engagement models are built around two moments: the sale and the claim. Between those two events, which can be a year or more apart, the insurer has almost no reason to appear in a customer’s life. This creates a structural dormancy problem that is different from banking or telecom, where daily transactions naturally create engagement opportunities. Without a deliberate engagement layer, an insurer’s app becomes something a customer opens only to file a claim or check a renewal date, which is also the worst possible context for a cross-sell conversation. The fix is not more communication volume. It is anchoring engagement to specific, data-driven moments, such as a policy anniversary, a life event signal, or a wellness milestone, so outreach feels timed rather than generic.

What to Look for in an Insurance Behavioral Analytics Platform, Through a Behaviour Mechanics Lens

The reward catalogue matters less than whether a platform can connect analytics to the right mechanic at the right moment:

  • Real-time trigger capability: instant rewards for insurance still need to fire the moment a customer completes an action like onboarding, not on a scheduled batch cycle days later.
  • Conditional, multi-step rewards: the platform should support rewards issued at one point in the journey, such as onboarding, but redeemable only on a future action, such as a cross-sell purchase, rather than every mechanic paying out immediately.
  • Customer big data ingestion: combining policy data, activity data, and engagement history into one customer view is the analytics foundation both mechanic types depend on.
  • Compliance and auditability: reward and campaign infrastructure needs to be auditable for regulated insurance markets, the same standard banking loyalty programmes are held to.
  • Behavioural attribution: every mechanic should be traceable to a specific outcome, such as retention or cross-sell conversion, not just an aggregate engagement score.

Instant Gratification and a Longer Cross-Sell Window, in Practice

A leading global insurer used two connected mechanics to close the gap between the sale and the next meaningful touchpoint. The first fired instantly: a reward issued the moment a customer completed a specific action, such as new policy onboarding or sharing weekly activity and lifestyle data. The second worked over a longer horizon: customers onboarded through the insurer’s banca (bancassurance) channel received rewards that were only redeemable upon purchase of an additional insurance product, extending the engagement window well past the initial sale. Combined, across a base of more than 26 million customers and $456 billion in assets under management, the approach delivered double-digit campaign ROI. Further detail is available in Perx’s published insurer case study at perxtech.com/insurer.

Behaviour Mechanics Mapped to Insurance Use Cases

Insurance Use Case Mechanic Type Example Mechanic Business Outcome Targeted
New policy onboarding Instant Reward on onboarding completion Reduce onboarding drop-off, strengthen first impression
Wellness or lifestyle data sharing Instant Reward for a specific data-sharing action Build a richer engagement and risk profile
Bancassurance (banca) cross-sell Conditional Reward redeemable only on future product purchase Extend engagement window, drive cross-sell conversion
Policy renewal or anniversary Conditional Milestone reward tied to renewal date Reduce lapse risk, reinforce retention
Claims journey engagement Instant Gamified status updates through the claims process Improve claims sentiment, reduce post-claim churn

From Engagement Data to Revenue and Risk Intelligence

Each mechanic in this model generates a data trail tied to a specific policyholder action. On their own, these mechanics improve retention and cross-sell conversion. Connected across a policyholder base, that same data starts to inform a broader question insurers are increasingly asking: which behaviours are early indicators of lapse risk, cross-sell readiness, or long-term value, at the individual policyholder level. This is the direction engagement platforms in insurance are heading in as a category, and it is a natural fit for the next phase of the platform for any insurer already running a connected instant-reward and conditional-reward model, since that data is already being generated.

How Perx Approaches This for Insurers

Perx supports both the instant rewards and the longer, conditional cross-sell rewards insurers need within a single compliance-ready architecture, so onboarding, wellness, and cross-sell data all feed the same customer view rather than sitting in separate systems. That same behavioural data is the foundation the next phase of the platform builds on as engagement platforms move toward connecting policyholder behaviour to retention and cross-sell outcomes at the individual level.

FAQs:

What is behavioral analytics in loyalty programs for insurance?
It is the practice of tracking specific policyholder actions, such as onboarding completion or lifestyle data sharing, and using that data to trigger real-time rewards or offers, rather than relying on a static annual point of contact.
They generally split into instant rewards, issued the moment a customer completes an action such as onboarding, and conditional rewards, earned at one point in the journey but only redeemable on a future action, such as a bancassurance cross-sell purchase.
Because the natural touchpoints in insurance are limited to the sale and the claim, which can be a year or more apart, leaving no structural reason for a customer to engage with the insurer in between.
Yes. A global insurer with 26M+ customers and $456B in assets managed used gamified, data-driven engagement to achieve double-digit campaign ROI, using instant-reward and conditional cross-sell mechanics.
Each mechanic generates behavioural data tied to a specific policyholder and outcome. Connected across a policyholder base, that data can begin to show which behaviours predict lapse risk, cross-sell readiness, or long-term value, which is the direction insurance engagement platforms are increasingly building toward.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

From Understanding Agentic Loyalty to Deploying It: A Sequencing Guide for BFSI Leaders

Agentic Loyalty for BFSI: From Theory to Deployment

From Understanding Agentic Loyalty to Deploying It: A Sequencing Guide for BFSI Leaders

Praveen Vadla

Senior Digital Marketing Manager | Jul 17, 2026

From Understanding Agentic Loyalty to Deploying It: A Sequencing Guide for BFSI Leaders

Capgemini says 75% of banks plan to adopt AI agents in customer service within two to three years. Far fewer have deployed. That gap between intent and execution is where the next round of competitive advantage in banking loyalty will be won or lost.

IN BRIEF

  • Capgemini’s Banking Top Trends 2026 names AI-driven loyalty, agentic AI, and gamification as the three plays banks are using to win customer engagement. The direction is now an analyst consensus, not a vendor claim.
  • The market signal is strong but the deployment is not: 75% of banks plan to adopt AI agents in customer service, yet most loyalty programmes still run on human-designed, human-triggered campaign cycles.
  • Moving to agentic loyalty is a sequencing problem, not a switch. Teams that try to jump straight to autonomous decision-making without the data and guardrail foundations underneath it tend to stall in pilot.
  • A verified APAC banking deployment shows what behaviour-triggered loyalty delivers at scale before full autonomy even enters the picture: 32x ROI and 709,000 users activated with Jenius (SMBC Indonesia).

If you have read our guide to what agentic AI means in loyalty programmes, you already understand the architecture: the four-layer Agentic Loyalty Stack, the six autonomous revenue agents that sit at the top of it, and why a monthly campaign cadence can no longer keep pace with individual customer behaviour.

So this is not another explainer. The question that matters for a senior BFSI team is no longer what agentic loyalty is. It is how to get from where the programme runs today to where the analysts say it needs to be, in an order that survives a risk committee, a CFO, and a two-year IT roadmap. This piece is about sequencing.

The direction is no longer in dispute

For most of the last decade, the case for AI-led loyalty in banking was a vendor argument. That has changed. In its Banking Top Trends 2026 report, the Capgemini Research Institute for Financial Services names three plays banks are using to connect with customers, and all three sit inside the loyalty and engagement layer: implementing agentic AI in customer contact centres, using gamified mobile-first platforms, and leveraging AI-powered loyalty programmes to personalise offers and services.

Capgemini frames AI-driven personalisation as a growth driver in its own right, arguing that financial institutions should shift to differentiated loyalty programmes that personalise rewards rather than offering generic incentives on data they already hold. The supporting evidence is worth putting in front of a board.

Capgemini Banking Top Trends 2026 – the case for AI-driven loyalty

Signal What it tells a BFSI leader
38% Of customers who switched financial institutions in 2024 did so because they were not satisfied with service quality. The churn driver is experience, not price.
73% Of card customers are motivated by personalised offers and rewards, which makes generic incentives a measurable revenue leak.
75% Of banks plan to adopt AI agents in customer service functions within the next two to three years.

Source: Capgemini Research Institute for Financial Services, Banking Top Trends 2026. Figures drawn from the published report; confirm against the source before citing externally.

Read the third number again, because it is the one that should shape your planning. Three-quarters of banks plan to adopt AI agents. Planning is not deploying. The market has reached consensus on the direction and has not yet moved on the execution. That is precisely the position in which first-mover advantage is still available.

The consensus has formed around the destination. It has not formed around who arrives first.

Why most agentic loyalty efforts stall in pilot

The failure pattern is rarely a failure of ambition. It is a failure of order. Teams read that agentic AI can detect a spend decline on Tuesday and intervene on Wednesday, and they try to buy the Wednesday intervention without first building the thing that detects Tuesday. Autonomous decisioning sits at Layers 3 and 4 of the stack. It cannot run on a foundation that does not yet exist at Layers 1 and 2.

There are three foundations that have to be in place before an autonomous agent can act safely inside a regulated bank:

Signal density before autonomy

A retail loyalty programme might see a customer a few times a week. A bank sees them dozens of times a day across channels. That signal density is what makes an agentic intervention precise rather than generic, but only if the signals are unified. Fragmented data is the single most common reason an agent has nothing useful to act on.

Guardrails before action

An autonomous agent in BFSI does not get to override compliance. It optimises within defined limits, on incentive disclosure, communication frequency, and data usage. Those limits have to be designed and agreed before the agent is allowed to execute, not retrofitted after a pilot raises a flag.

A defined behavioural target before a reward

An agent with a vague objective produces vague outcomes. The objective has to be specific and measurable, reduce 90-day primary-account dormancy, lift credit-card reactivation, before the system has anything to optimise toward. A deployment without a measurable behavioural target is not an agentic deployment. It is automation with better marketing.

A sequencing model that survives a risk review

The progression below is deliberately ordered so that each phase produces a defensible result before the next one starts. The point is not speed for its own sake. It is to reach autonomous decisioning with the data, the guardrails, and the internal trust already in place.

PHASE 01 · FOUNDATION

Unify the behavioural signal

Bring the high-frequency signals a bank already generates into one behavioural layer. The deliverable is not a campaign. It is a single, real-time view of customer behaviour that later phases can act on. Most BFSI organisations sit here today.

PHASE 02 · PREDICTION

Add predictive intelligence and prove it quietly

Layer predictive models onto the unified signal, spend-decline detection, lapse probability, redemption likelihood, and validate their accuracy against real outcomes before anything acts on them. This phase builds the internal evidence the risk committee will ask for in Phase 3.

PHASE 03 · GUARDED AUTONOMY

Let one agent act inside tight guardrails

Move a single, well-bounded use case, often offer optimisation, from prediction to autonomous execution, within strict compliance limits and on a defined behavioural target. One agent, fully measured, builds the trust that funds the rest.

PHASE 04 · SCALE

Extend to the full agent set

With the foundation, the evidence, and the guardrails proven, extend autonomy across the remaining revenue agents. This is the Layer 3 to Layer 4 progression Capgemini’s two-to-three-year window is describing, reached on a footing that holds up under scrutiny.

PROOF POINT · APAC BANKING

What behaviour-triggered loyalty delivers before full autonomy

It is worth being precise about what is already proven versus what is still forward-looking. The deployment with Jenius (SMBC Indonesia) was behaviour-triggered, rules-based loyalty, behaviourally designed and measurable, not fully agentic AI. It is a marker of what the foundation phases can deliver at scale, and a sense of the headroom the agentic layers add on top.

32x
Return on investment
709K
Users activated

What this means for your next planning cycle

The honest read of the Capgemini data is that the industry has agreed on where loyalty is going and has not yet moved. For a BFSI team, that produces a narrow and valuable window. The work that creates advantage in the next twelve months is not buying an autonomous agent. It is building the foundation that an autonomous agent needs, in an order that earns internal trust at each step, so that when the rest of the market begins deploying in two to three years, your programme is already there.

That is the difference between a platform that drives revenue and one that merely reports on it. The destination is settled. Sequencing is the advantage.

FAQs:

What is the difference between agentic AI and the AI our loyalty platform already uses?

Most loyalty AI today is predictive or assistive: it tells a team that a customer is likely to churn, then waits for a human to decide and act. Agentic AI acts on the prediction autonomously, selecting an intervention from a defined toolkit, executing it through the right channel at the right time, and recording the outcome to improve future decisions, all within compliance guardrails. The defining difference is autonomous execution against a measurable objective.

Yes, when it is designed to. A well-built agent does not override compliance rules on incentive disclosure, communication frequency, or data usage. It optimises within those defined limits. The guardrails have to be agreed before the agent is allowed to execute, which is why guarded autonomy sits at Phase 3 of a sound sequencing model rather than at the start.

Because autonomous agents sit at the top of the stack and depend on foundations beneath them: unified behavioural signal, validated predictive models, and agreed guardrails. Skipping to execution without those in place is the most common reason agentic loyalty efforts stall in pilot. Sequencing exists to reach autonomy on a footing that survives a risk review.

Capgemini’s Banking Top Trends 2026 reports that 75% of banks plan to adopt AI agents in customer service functions within two to three years. That timeline is the planning window. Teams that build the foundation now are positioned to be live when the broader market is still beginning.

Praveen Vadla

Praveen Vadla is Senior Digital Marketing Manager at Perx Technologies. With over 10 years of experience in B2B SaaS marketing across the US and Southeast Asia, he focuses on customer loyalty, engagement, and retention strategy. He writes on how brands build lasting customer relationships in a mobile-first economy. Connect with Praveen on LinkedIn.

Recommended for you

Open Finance

Open Finance in Malaysia: What Banks Need to Get Right | Perx

Open Finance

Samit Deb

Director of Enterprise Sales | Jul 13, 2026

Open Finance Is Coming to Malaysia. Is the Customer Experience Ready?

In Brief

Bank Negara Malaysia is rolling out a national Open Finance framework. Industry feedback on the exposure draft closed in March 2026, and the central bank’s most recent public remarks now frame implementation as phased, starting from 2027, as part of a new Financial Sector Blueprint running through 2030. It is part of a wider Southeast Asian pattern already visible in Singapore’s SGFinDex and Indonesia’s SNAP standard. For banks, this means customer financial data will soon move between institutions with consent, not just within them. The regulatory and technical questions are being actively worked through. The customer experience question, whether people will actually understand and trust what they are opting into, is being worked through far less. Banks that treat open finance as a trust-building moment, not just a compliance deadline, are the ones likely to keep the customer relationship once data becomes portable.

Open Finance Is Not a Malaysia Story. It Is a Regional One.

Southeast Asia has been building toward this for several years, market by market. Singapore’s Financial Data Exchange (SGFinDex), a joint initiative between the Monetary Authority of Singapore and GovTech, lets individuals pull financial data from participating banks, insurers, and government agencies into one consolidated view using Singpass authentication. Indonesia has taken a phased route through Bank Indonesia’s SNAP standard, moving from payment API standardisation toward a broader open finance roadmap that is expected to extend into lending, insurance, and investment data.

Malaysia is now formalising its own version. Bank Negara Malaysia released an exposure draft on Open Finance in November 2025, describing a consent-based framework for sharing customer information between data providers and data consumers in a secure, interoperable, and timely manner. Industry feedback on the draft closed on 1 March 2026. Technical development is being led by PayNet with seven banks and the Employees Provident Fund, and an early pilot had originally been targeted for mid-2026. More recently, BNM’s own leadership has framed the rollout differently: at a July 2026 industry address, the central bank governor described Open Finance as a foundation of a new Financial Sector Blueprint covering 2027 to 2030, with implementation now positioned as phased and starting from 2027. The finalised framework had not yet been published at the time of writing, so the exact phasing and start date should be treated as directional and worth reconfirming closer to publication.

The pattern across all three markets is the same: data moves with consent, in standard formats, through infrastructure built by regulators and industry together rather than bank by bank. In Malaysia’s case, the exposure draft also proposed that larger banks would onboard first, before the requirement extends to a wider set of financial service providers, a sequencing likely to carry through regardless of the exact start date. That is the shift banks need to plan for now, regardless of exactly when their market’s rollout date lands.

What Open Finance Actually Changes

Open banking, the first wave of this shift globally, was mostly about payment initiation and account information, driven by regulation like the UK’s Open Banking standard, which the Competition and Markets Authority mandated in 2017 for the country’s nine largest banks and building societies, known as the CMA9, and the EU’s PSD2. Open finance goes further. It extends the same consent-based sharing model to savings, credit, insurance, and investment data, giving a fuller picture of a customer’s financial life, not just their transactions.

For banks, that is a meaningful change in what “knowing your customer” means. A financial institution requesting a customer’s data could, for example, pull months of history from another institution to speed up a loan application, or let a customer view several credit card statements in one place instead of switching between banking apps. The upside is real: faster approvals, better-informed lending, and products built on a fuller financial picture. The complication is that the same visibility works both ways. If a bank can see more of a customer’s financial life elsewhere, other institutions can see more of that customer’s life at this bank too.

What Banks Are Actually Worried About

Conversations with banks across the region tend to circle back to a consistent set of concerns, and they are reasonable ones:

  • Data control and residency. Where is the data stored, can it leave the country, and who is accountable if something goes wrong downstream, after the data has already been shared.
  • Regulatory exposure. Consent frameworks, audit requirements, and jurisdictional data rules differ by market, and getting ahead of them takes real compliance investment.
  • Commoditisation risk. If a customer’s financial data becomes portable, the customer becomes more portable too. A bank that has spent years building a relationship on convenience or inertia may find that no longer holds once switching is a few consent taps away.
  • Integration complexity. Most banks are working with core systems that were never designed to expose structured, real-time data externally, which makes compliance a genuine engineering project, not a policy memo.

These are not hypothetical concerns. Legal analysts covering the exposure draft point out that today’s data-sharing practices, largely PDF statements sent by email or documents couriered between institutions, leave customers with little visibility or control over where their information goes, which is exactly the gap Open Finance is designed to close, and precisely the operational shift banks now have to absorb.

What Customers Are Actually Worried About

Less discussed, but just as important, is the other side of the consent screen. Customers are not automatically enthusiastic about sharing more financial data, even when the framework is designed to protect them. The concerns tend to be simpler than the regulatory ones, but no less real:

  • “What am I actually agreeing to?” Most consent flows are written for compliance, not comprehension. A legal disclosure is not the same as an explanation.
  • “What’s in it for me?” Without a visible, immediate benefit, sharing data feels like a one-sided request, even when the long-term upside (faster approvals, better rates, less paperwork) is genuine. That gap is exactly where a well-designed loyalty or rewards layer earns its keep, giving the customer something they can feel the moment they say yes, rather than a promise they have to trust will show up later.
  • “Will this be used against me?” A reasonable fear is that more visibility means more scrutiny, sharper risk pricing, or unwanted product pushing, rather than something that works in the customer’s favour.
  • “What happens if I say no?” Today, that usually means nothing. No follow-up, no explanation of what they are missing, no path back in later if their situation changes.

Any bank rolling out open finance well has to answer both sets of concerns at once, the regulator’s and the customer’s, and they are not the same conversation.

Where the Experience Breaks Today

Across most current data-sharing and consent flows, regardless of market, the pattern looks the same. A customer is handed a legal consent screen with limited context, asked to accept or decline, and then nothing happens with that decision either way. If they accept, they rarely understand what they have shared or why. If they decline, the bank rarely finds out why, and almost never follows up. The interaction closes the moment the toggle is set, either way. That is not a technology failure. It is a design failure, and it exists independently of any particular platform or vendor. It happens because consent has been built as a legal checkpoint, not a customer conversation.

What a Well-Designed Open Finance Experience Looks Like

Open finance done well flips that design failure into an engagement opportunity. A few principles worth building around:

Education before consent, not instead of it. A short, plain-language explanation of what is being shared, why, and what the customer gets in return does more for trust than any length of legal text. This does not replace the compliance disclosure, it comes before it.

Understanding “no,” not just recording it. When a customer declines to share data, that is useful information, not a dead end. Understanding whether the hesitation is about a specific data type, a trust issue, or simple inattention lets a bank address it directly, potentially through a relationship manager follow-up rather than a repeated pop-up.

Recognising that one reward model does not fit everyone. A younger, digitally native customer and a long-standing older customer are not motivated the same way. Probability-based, game-like mechanics can work well for one segment and feel patronising or confusing to another, who may respond better to a straightforward, immediate reward for completing a step.

Turning visibility into relevance, not just retention tactics. Once a bank has a fuller picture of a customer’s financial life, the useful move is a genuinely relevant offer at the right moment, not a generic upsell campaign that ignores the context the bank just gained permission to see.

Three Open Finance Customer Journeys That Get This Right

To make this concrete, here are three anonymised journey concepts that show what a thoughtfully designed open finance experience can look like in practice. These are illustrative patterns, not descriptions of any specific bank’s live programme.

The onboarding journey that explains itself. 

Instead of a bare consent toggle, a customer arriving at the open finance opt-in sees a short explainer, in plain language, on what data sharing means and what they stand to gain, such as faster approvals or a consolidated view of their finances. A brief follow-up question then checks understanding and willingness, rather than assuming silence means comprehension. If the customer is not ready to share, the flow captures why, so the bank can address the specific concern rather than simply representing the same request later.

Onboarding Journey

The engagement journey that treats segments differently. 

Two customers complete the same onboarding step, but the reward experience differs by what motivates them. One is offered a game-like, probability-based reward that adds a moment of anticipation. The other receives an immediate, guaranteed reward with no extra steps. Neither approach is “better,” they are matched to what actually drives each group to engage, rather than a single mechanic applied uniformly across the customer base.

Engagement Journey

The retention journey that rewards good financial behaviour. Rather than only reacting when a customer withdraws funds or shows signs of disengagement, a milestone-based journey rewards the absence of a negative behaviour, for instance recognising a customer for each consecutive period they maintain a balance rather than draw it down, with a meaningful reward at a specific milestone. It is a small shift, from campaigns that chase customers after they’ve already started leaving, to ones that recognise and reinforce the behaviour a bank actually wants to see more of.

Retention Journey
None of these require exotic technology. They require treating open finance as a customer relationship to design, not only a data pipe to build.

Where Open Finance and Loyalty Are Heading Next

The open finance rollout will happen whether or not any individual bank gets the experience right. What is less certain is which banks will use it to deepen customer relationships and which will simply treat it as a compliance milestone to clear.

This is also where the next phase of what Perx is building becomes relevant. Alongside the loyalty and engagement journeys banks run today, we are working on giving banks a much fuller, real-time understanding of a customer’s overall financial health, not just their activity with a single product, so that the offers and journeys built on top of open finance data are genuinely useful rather than generic. More on that soon.

If you are working through what your own open finance rollout should look like, from consent design to the engagement layer sitting on top of it, we would be glad to talk it through.

FAQs

Common questions.

What is the difference between open banking and open finance?

Open banking generally refers to sharing payment and account information, often driven by regulation such as the UK’s Open Banking standard or the EU’s PSD2. Open finance extends the same consent-based data-sharing model to a broader set of financial products, including savings, credit, insurance, and investments.

When is open finance launching in Malaysia?

Bank Negara Malaysia released an exposure draft on Open Finance in November 2025, with industry feedback closing in March 2026. An early pilot had originally been targeted for mid-2026, but as of a July 2026 industry address, BNM’s governor has framed the rollout as a phased implementation starting from 2027, as part of a new Financial Sector Blueprint covering 2027 to 2030. Larger banks are expected to onboard first.

Which other Southeast Asian markets have open finance frameworks?

Singapore’s SGFinDex, run jointly by the Monetary Authority of Singapore and GovTech, has been live for several years and covers banks, insurers, and government agencies. Indonesia’s Bank Indonesia has developed the SNAP standard for open API payments, with a broader open finance roadmap expected to extend into lending, insurance, and investment data.

Why do customers hesitate to share financial data, even with regulatory protection?

Most hesitation comes down to unclear communication rather than distrust of the regulation itself. Customers commonly want to know what exactly is being shared, what they get in return, and whether visibility could be used against them, such as through sharper pricing or unwanted product offers.

How can banks make open finance consent flows more effective?

Plain-language education before the consent screen, understanding the specific reason behind a decline rather than just recording it, and following up appropriately all help. Consent works better as an ongoing conversation than a one-time legal gate.

Samit Deb

Samit Deb is Director of Enterprise Sales at Perx Technologies in Singapore. ACA and CISA qualified, with a background at PwC and KPMG, he writes on open finance, BFSI, and AI-enabled customer engagement. Connect on LinkedIn.

Recommended for you

Loyalty Engagement Platform Built for the Mobile-first Economy
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.